Formation & ownership
Entity Selection & Setup
Compare LLC, corporation, and partnership structures alongside ownership, tax elections, liability, and financing plans.
Read the related answer
Shin Law Office · Northern Virginia
Build the company.
Plan for its next move.
Starting a business, adding an owner, or buying your company’s building connects decisions that are easy to treat separately. We help align the entity, ownership agreements, property structure, and financing documents before you commit.
Legal guidance from formation through financing and closing. Shin Law Office is not a lender.
Business formation establishes the company’s legal structure and ownership framework. SBA 504 financing can help an eligible business acquire qualifying fixed assets, including property it uses for operations.
The entity that owns the property, the operating business, their lease, and the people signing guaranties need to fit the transaction. Shin Law Office handles the legal review and documentation while the bank, Certified Development Company, and SBA perform their respective financing functions.
Sources: SBA: 504 loan program · 13 CFR § 120.111: Eligible Passive Companies
Start with the decision in front of you
Choose your stage and the issue to see useful records and a relevant answer.
Step 1 of 2
Select the closest starting point.
This guide does not select an entity, make a tax election, apply for a loan, or determine eligibility.
From the foundation to the financing
Describe the issue in your own words, from an ownership agreement to a holding company or personal guaranty.
Try “operating agreement,” “504 down payment,” “separate property LLC,” or “EIN.” Leave out private financial details.
Showing all six topics.
Compare LLC, corporation, and partnership structures alongside ownership, tax elections, liability, and financing plans.
Read the related answerPrepare operating agreements, bylaws, shareholder terms, and approvals addressing control, contributions, exits, and borrowing.
Read the related answerReview project uses, occupancy, ownership, contribution requirements, and the legal structure with your bank and CDC.
Read the related answerAssess an Eligible Passive Company structure and its lease, ownership, occupancy, and operating-company obligations.
Read the related answerReview notes, liens, guaranties, covenants, title issues, and closing conditions before the business and owners sign.
Read the related answerCoordinate entity filings, EIN steps, registered-agent requirements, and applicable licenses and ongoing business obligations.
Read the related answerChoose “All topics” to broaden the results, or contact the firm about the documents and decision.
Discuss your situationBusiness formation in Virginia
A useful formation plan addresses how the business will be owned, managed, funded, and used. The documents should reflect the owners’ actual agreement.
Compare LLC, corporation, and partnership structures against the business’s activities, owners, management, and future investment plans. An existing company may need document changes rather than a new filing.
Sources: Va. Code § 13.1-1011: LLC articles · IRS: LLC tax classifications
Address contributions, voting, distributions, borrowing authority, transfers, deadlock, and exits. A standard form may leave the decision that matters most unresolved.
“LLC” describes a state-law entity. “S corporation” describes a federal tax election for an eligible entity. Coordinate the choice, eligibility, and filing timing with tax advisers.
Sources: IRS: LLC tax classifications · IRS: S corporations
LLC liability protections and a personally signed loan obligation answer different questions. Before borrowing, identify who is signing for the business, who is signing individually, and what each document requires.
Sources: Va. Code § 13.1-1019: LLC liability · 13 CFR § 120.160: Loan conditions
Understand the 504 structure
A common 504 structure combines a 50% bank loan, 40% CDC/SBA-backed financing, and 10% borrower contribution. That is a starting illustration, not a promise that every project qualifies or uses the same split.
The program focuses on eligible long-term fixed assets. Owner-used business property, construction, renovations, and qualifying equipment may fit. The proposed use, repayment ability, ownership, size, and other current requirements still need review.
Sources: SBA: 504 loan program · 13 CFR § 120.910: Borrower contributions · 13 CFR § 120.920: Third-party lending
| Project circumstances | Borrower contribution | What to confirm |
|---|---|---|
| Standard circumstances | At least 10% | The business and property must still satisfy the program and lender requirements. |
| Business operating for two years or less | At least 15% | The rule also looks to the operating company when an Eligible Passive Company borrows. |
| Limited or single-purpose building or structure | At least 15% | The lender and CDC must assess the actual property and project. |
| Both of the above conditions apply | At least 20% | A new business combined with a qualifying special-purpose property increases the minimum. |
These percentages apply to project cost excluding administrative costs. A lender or transaction may require more. The source of the contribution and eligible project costs also need review.
Sources: 13 CFR § 120.910: Borrower contributions · 13 CFR § 120.882: Eligible project costs
The general limit is $5 million in outstanding 504 financing for the borrower and affiliates. Certain qualifying manufacturing and energy projects allow $5.5 million per project. The bank loan and borrower contribution are separate.
Sources: 13 CFR § 120.931: 504 lending limits
The CDC/SBA portion provides fixed-rate financing. The bank portion may have different rate, reset, maturity, prepayment, and amortization terms. Review the actual commitments together.
Sources: SBA: 504 loan program · 13 CFR § 120.920: Third-party lending
Business use of the property
The business’s actual use of the property matters. Existing buildings and new construction have different occupancy and leasing rules.
Review the rentable area, floor plan, existing tenants, proposed operations, and any expansion assumptions before relying on financing. Zoning, permits, and the purchase contract may raise separate questions.
Sources: 13 CFR § 120.131: Building occupancy · 13 CFR § 120.110: Ineligible businesses
Review the occupancy questionsProperty ownership and the operating business
Some transactions use an Eligible Passive Company, or EPC, to hold property that it leases to the operating company. This is a specific program exception, not automatic permission to finance a passive investment.
The lease and financing documents need to work together. Review the permitted rent, remaining lease term, lien priority, assignment of rents, and the operating company’s guarantor or co-borrower role.
Sources: 13 CFR § 120.111: Eligible Passive Companies · 13 CFR § 120.160: Loan conditions
Explore the numbers
Compare the proposed borrower, bank, and CDC/SBA shares, then estimate principal and interest using your own assumptions.
Example rates only: the prefilled 8.0% and 6.5% rates are illustrations, not current loan quotes. Ask your lender and CDC for applicable terms.
Illustrative allocation
Excludes financing and servicing fees, taxes, insurance, closing costs, rate resets, and balloon balances. Financed fees can change the loan principal and actual payment.
Discuss the legal structureSources: 13 CFR § 120.910: Borrower contributions · 13 CFR § 120.920: Third-party lending · 13 CFR § 120.930: 504 amount · 13 CFR § 120.931: 504 lending limits · SBA: 504 loan program
Before the signatures
A loan commitment, personal guaranty, and company resolution each serve a different purpose. Review the complete package while there is time to address unresolved terms.
Review the note rate, payment schedule, maturity, balloon risk, fees, prepayment terms, and any variable-rate provisions. The monthly payment alone does not describe the cost or refinancing risk.
Identify personal and entity guarantors, pledged assets, default remedies, and continuing obligations. Owners with at least 20% interests generally face SBA guaranty requirements; others may also be required.
Sources: 13 CFR § 120.160: Loan conditions · 13 CFR § 120.111: Eligible Passive Companies
Match the entity names, ownership records, approvals, lease, title documents, insurance, and lender checklist. Calendar actual purchase and financing deadlines.
An EIN, entity filing, local license, and occupancy approval do different jobs. Review the requirements for the business activity and each location, including applicable tax and employment registrations.
Sources: IRS: Employer identification numbers · Va. Code § 13.1-1015: Registered agents · SBA: Launching a business
FinCEN’s current guidance exempts U.S.-created entities from federal BOI reporting. Certain foreign-created entities may still have duties. Bank and lender ownership-information requests are separate.
Read the current BOI answerPrepare for a useful conversation
Start with what exists now. You do not need to have every answer before discussing the legal work.
How working with us begins
Discuss the business, owners, project, existing obligations, and any immediate deadlines.
Prepare or review entity, governance, ownership, and property documents appropriate to the matter.
Work through legal requirements with the client, lender, CDC, tax advisers, and transaction team.
Address the agreed documents, authority, closing conditions, and responsibilities after signing.
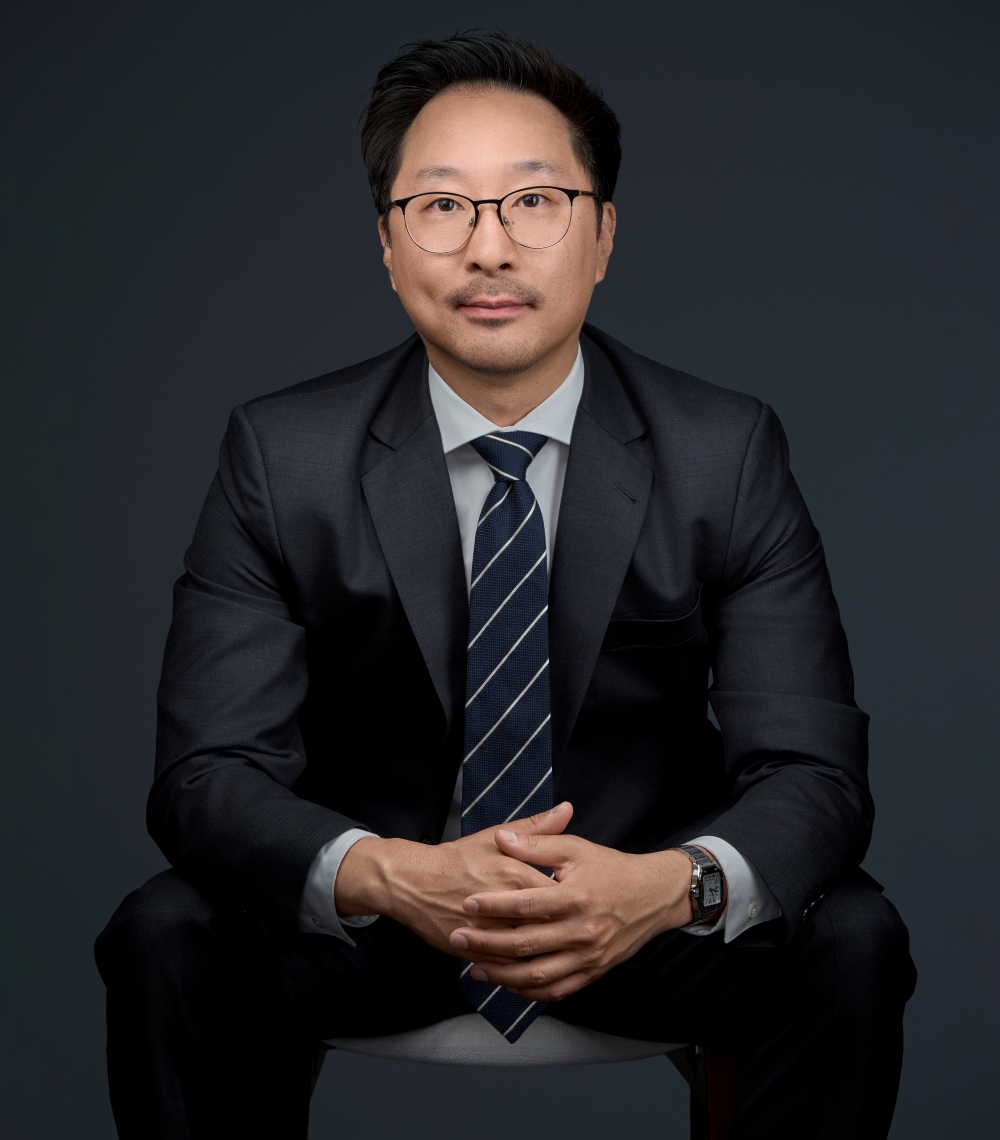
Shin Law Office
Founder
Business owners make formation and financing decisions while managing the work of running the company. A useful legal review connects the paperwork to the ownership, property, and obligations behind it.
Shin Law Office assists with business formation and the legal side of SBA 504 transactions. Contact the firm to discuss your situation and the scope of representation.
Meet Anthony I. ShinNorthern Virginia
Shin Law Office helps Northern Virginia business owners coordinate entity formation, ownership documents, and the legal work surrounding property and SBA 504 financing.
Tell us whether you are forming a company, reviewing an existing structure, buying property, or approaching a loan closing. Include any known deadlines when arranging a consultation.
Request a consultationOffice: 571-445-6565
Cell: 571-215-8823
Fax: 703-442-8938
118 Edwards Ferry Road, N.E.
Unit 110
Leesburg, VA 20176
8300 Arlington Boulevard
#B2
Fairfax, VA 22031
Business formation & SBA 504 FAQs
These answers explain common legal and program questions. The actual transaction, current rules, and lender and CDC requirements determine the next steps.
Discuss your questionA business formation attorney helps select and document the legal structure, ownership, management authority, and agreements the business will use. The work can also include coordinating financing, property ownership, registrations, and lender requirements. The scope depends on the business and the engagement.
Sources: Va. Code § 13.1-1011: LLC articles · Va. Code § 13.1-1023: Operating agreements
The choice depends on the owners, management preferences, investment plans, tax treatment, and liability concerns. An LLC and a corporation are different state-law structures. Review the legal choice alongside tax advice rather than assuming one structure is best for every business.
Sources: Va. Code § 13.1-1011: LLC articles · IRS: LLC tax classifications · IRS: S corporations
Not exactly. S corporation status is a federal tax election for an eligible entity. A qualifying LLC can elect corporate tax treatment and may qualify for S corporation treatment. The entity filing and tax election are separate steps, with eligibility and timing requirements to review with a tax adviser.
Sources: IRS: LLC tax classifications · IRS: S corporations
Virginia law generally does not require an operating agreement to be written unless the articles or a written agreement require it. A tailored written agreement is still useful to document ownership, management, contributions, voting, distributions, transfers, and exits. Lender or transaction requirements may also call for written evidence of authority.
No. Virginia law generally protects a member from company liabilities solely because of membership, but a separate personal guaranty creates a different obligation. Entity formation does not erase a guaranty or every other basis for personal liability. Review the documents the business and each owner are asked to sign.
Sources: Va. Code § 13.1-1019: LLC liability · 13 CFR § 120.160: Loan conditions
Formation creates the entity under state law. An employer identification number is a federal tax identifier issued by the IRS; it does not create the entity or replace a required license. An EIN obtained directly from the IRS has no IRS application fee. A Virginia LLC also needs a qualifying registered agent and registered office.
Sources: Va. Code § 13.1-1011: LLC articles · IRS: Employer identification numbers · Va. Code § 13.1-1015: Registered agents
No. State entity formation is separate from local business licensing, zoning, occupancy, professional licensing, and applicable tax or employer registrations. The requirements depend on the activity and location. Check them before opening or relying on a proposed commercial property for the business.
Sources: SBA: Launching a business
Under FinCEN’s current guidance reviewed October 3, 2026, entities created in the United States are exempt from federal beneficial ownership information reporting. Certain entities formed under foreign-country law and registered in the United States may still have reporting duties. This exemption does not eliminate separate bank, lender, tax, or state information requirements.
Yes. The firm can review existing filings and agreements, ownership and management authority, and proposed changes connected with growth or financing. A new entity is not always needed. The existing obligations, tax consequences, lender requirements, and transaction objectives should be reviewed before restructuring.
SBA 504 financing supports eligible long-term fixed assets, such as owner-used commercial property and qualifying equipment. A project commonly combines a bank or other third-party loan, a CDC/SBA-backed portion, and a borrower contribution. The fixed-rate feature relates to the CDC/SBA portion; the separate bank loan has its own terms.
Sources: SBA: 504 loan program · 13 CFR § 120.920: Third-party lending
No. Shin Law Office provides legal guidance on entities, agreements, financing documents, and closing. The bank, Certified Development Company, and SBA perform their respective lending, eligibility, and approval functions. Legal representation does not guarantee financing or a particular rate or closing date.
Sources: SBA: 504 loan program
Eligible projects can include commercial buildings, land, construction or renovation, and qualifying long-term machinery and equipment. Related project costs may qualify under the rules. The CDC and lender must assess the specific assets, project budget, business use, and documentation.
Sources: SBA: 504 loan program · 13 CFR § 120.882: Eligible project costs
504 is not a general inventory or working-capital program, and a standalone passive rental-property investment is generally ineligible. Its focus is eligible fixed assets used by an operating business. Certain refinancing structures have separate rules, so ask the CDC to assess the actual use of proceeds rather than treating all business expenses as eligible.
Sources: SBA: 504 loan program · 13 CFR § 120.882: Eligible project costs · 13 CFR § 120.110: Ineligible businesses
The rules permit applicable industry size standards or an alternative financial test. Under that alternative, the applicant and affiliates generally must have tangible net worth no more than $20 million and average net income after federal income taxes, excluding carryover losses, no more than $6.5 million for the preceding two completed fiscal years. Other eligibility and credit requirements still apply.
No. Under 13 CFR 120.910, the minimum is generally 10 percent of project cost excluding administrative costs, 15 percent if the business has operated for two years or less, and 15 percent for a limited or single-purpose building or structure. Both conditions together generally require at least 20 percent. A particular transaction may require more.
A new business is not automatically excluded, but it must meet applicable program and credit requirements. A business operating for two years or less generally triggers at least a 15 percent contribution, or 20 percent when the limited or single-purpose property condition also applies. The lender and CDC must evaluate the business plan, repayment ability, and other criteria.
Sources: SBA: 504 loan program · 13 CFR § 120.910: Borrower contributions
No. The 504 lending limit applies to the 504 portion, not automatically to the entire project including bank financing and borrower funds. The general outstanding 504 limit is $5 million for a borrower and affiliates. Certain qualifying manufacturing or energy projects have a $5.5 million per-project limit. Existing debt, eligible fees, and program conditions need review.
Sources: 13 CFR § 120.931: 504 lending limits
Not necessarily. The CDC/SBA-backed portion provides long-term fixed-rate financing. The bank or other third-party loan has separate terms and may use a fixed or variable rate, a rate reset, or an earlier maturity. Read both sets of documents before comparing total borrowing costs.
Sources: SBA: 504 loan program · 13 CFR § 120.920: Third-party lending
SBA lists 10-, 20-, and 25-year maturities for 504 financing. The appropriate term depends on the financed assets and applicable requirements. The bank’s repayment schedule and maturity are separate. A bank loan can have a balloon balance if it matures before its amortization schedule ends.
Sources: SBA: 504 loan program
For an existing building acquired, renovated, or reconstructed with the financing, the borrower generally must permanently occupy and use at least 51 percent of the rentable property. Up to 49 percent may be permanently leased. If an Eligible Passive Company owns it, the operating company or companies must satisfy the occupancy rules.
Sources: 13 CFR § 120.131: Building occupancy
The business generally must permanently occupy and use at least 60 percent of the rentable property. Up to 20 percent may be permanently leased. It must plan to use some of the remaining space within three years and all remaining space not permanently leased within ten years. The CDC should review the specific occupancy and expansion plan.
Sources: 13 CFR § 120.131: Building occupancy
Potentially. The SBA Eligible Passive Company exception allows a qualifying property-holding entity to lease eligible assets to an eligible operating business. Both the structure and documents must satisfy program conditions. Creating a separate LLC alone does not establish eligibility, remove guaranties, or make a passive investment property eligible.
Sources: 13 CFR § 120.111: Eligible Passive Companies · 13 CFR § 120.110: Ineligible businesses
The lease must be written, subordinate to the SBA lien, and supported by an assignment of rents. Its remaining term, including qualifying renewal options controlled solely by the operating company, must cover the loan term. Rent is limited to the loan payment and permitted direct property-holding expenses. The operating company must be a guarantor or co-borrower.
Owners with at least a 20 percent interest generally must guarantee an SBA business loan. In an Eligible Passive Company structure, the rule reaches qualifying owners of either the property company or the operating company. Additional guarantors may be required for credit or other reasons. A smaller ownership percentage is not an automatic exemption.
Sources: 13 CFR § 120.160: Loan conditions · 13 CFR § 120.111: Eligible Passive Companies
Review the commitments, notes, guaranties, liens, collateral, covenants, default provisions, prepayment terms, and conditions to funding. Entity authority, title, insurance, lease terms, purchase contingencies, and any environmental obligations should be coordinated with the transaction team. The review should occur before the scheduled signing.
There is no single timeline for every project. Eligibility review, underwriting, appraisals, environmental work, title issues, construction, approvals, and document completion can affect timing. Ask the lender and CDC about the specific milestones and any interim financing. Do not assume a consultation or preliminary discussion satisfies a purchase-contract deadline.
No. It models a proposed allocation and principal-and-interest payments using the rates and periods entered. It excludes financing and servicing fees, taxes, insurance, closing costs, rate changes, and bank balloon balances. It does not underwrite the business, determine eligibility, or account for existing affiliate debt. Replace the example rates with lender assumptions.
Some refinancing can qualify, but the rules distinguish different structures and impose conditions on the debt, collateral, business use, and eligible costs. A conventional loan or ownership change is not automatically eligible. Have the CDC and counsel review the current rule and complete transaction before relying on 504 refinancing.
Bring existing entity filings and agreements, an ownership chart, the project budget, any purchase contract or lease, lender or CDC correspondence, and proposed loan documents. Identify the desired outcome and any deposit, financing, or closing deadlines. Financial and tax records can be shared through a suitable channel when needed.
Shin Law Office has offices in Leesburg and Fairfax, Virginia. Call 571-445-6565 or use the contact page to request a consultation about formation, ownership documents, or the legal side of 504 financing. The firm is not a lender, and sending an inquiry does not establish representation or secure financing.
From the first filing to the next investment
Discuss the business, the owners, and the property or financing plans. We can help identify the legal work needed before the next agreement is signed.
Legal services are separate from lending, underwriting, and tax advice. Contacting the firm does not establish representation or secure a loan.
Primary sources reviewed October 3, 2026. Confirm current rules and transaction requirements with counsel, tax advisers, the lender, and the CDC as appropriate.
General information, not legal, tax, or financial advice for a particular transaction. Shin Law Office is not a lender. Illustrations and calculator outputs do not establish eligibility, underwriting approval, or actual borrowing costs. Representation follows a conflicts check and an agreed engagement.
Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.
Copyright © 2026 Shin Law Office, PLC. All rights reserved.
Powered by HILARTECH, LLC
Copyright © 2026 Shin Law Office, PLC. All rights reserved.
Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.