Shin Law Office · Surety transactions & litigation

Surety Bond Attorneys in Northern Virginia

Understand the bond.
Protect the business behind it.

A bond claim can put cash flow, project completion, and future work under pressure. Whether you need to get paid, answer a claim, or understand an indemnity agreement before signing, we help you assess the documents, deadlines, and options.

Serving contractors, subcontractors, suppliers, and businesses from Leesburg and Fairfax.

Bond & GIA reviewClaims & defenseNotice & deadlines

What does a surety bond attorney help with?

A surety bond attorney reviews the bond, underlying contract, and indemnity agreement; evaluates claims and defenses; and addresses notices, deadlines, collateral, reimbursement, and resolution. The analysis starts with your role, the bond type, the project, and the law that applies.

A construction bond backs specified obligations to others. It does not automatically protect the contractor from having to repay the surety under a separate agreement.

Sources: FAR 28.001: Bond, bid guarantee, and bond-type definitions · Fidelity & Deposit Co. v. Bristol Steel & Iron Works, Inc., 722 F.2d 1160 (4th Cir. 1983): Contractual indemnity

Need payment?Identify the bond, protected claimant, and required process.
Facing a demand?Identify the obligation, supporting evidence, and response date.

Start with the decision in front of you

You do not need to know the legal label.

Choose your situation, then the issue that needs attention. The guide suggests records to gather and a related answer to read.

A default notice, collateral demand, or unpaid public-project balance may need prompt review. Keep the complete papers and delivery records. Mention any stated deadline, last work date, termination, or court hearing when you contact the firm.

The bond, the claim, and the indemnity

Find the issue behind the paperwork.

An unpaid invoice, a project default, and a surety demand can involve overlapping documents and different legal rights. Search in your own words to find a useful starting point.

Bonds & planning

Bid, Performance & Payment Bonds

Identify the promise, the parties protected, the bond amount, and the conditions for a claim. Bid, performance, and payment bonds serve different purposes.

Read the related answer
Bonds & planning

General Indemnity Agreement Review

Review who is signing, the obligations covered, personal liability, collateral, settlement authority, and the terms that may continue after a project ends.

Read the related answer
Claims & payment

Bond Claims & Defense

Connect the claimed amount or alleged failure to the bond, contract, evidence, and available defenses. A claim submission and a lawsuit are separate steps.

Read the related answer
Claims & payment

Miller Act & Little Miller Act

Check the governing public-project law, contracting tier, notice method, last qualifying work date, and filing deadline. Federal and Virginia rules differ.

Read the related answer
Default & exposure

Default, Collateral & Reimbursement

Separate the project default, the bond response, a collateral demand, and reimbursement under the GIA. Each can involve different conditions and evidence.

Read the related answer
Bonds & planning

Bonding Capacity & Surety Relationships

Address agreements, ownership changes, outstanding claims, and documentation alongside the surety’s underwriting review. Legal planning cannot promise bond approval.

Read the related answer

The relationship behind the bond

Three parties can have very different interests.

The principal undertakes the bonded obligation. The obligee receives the bond’s protection. The surety backs the promise on the terms stated. On a subcontract bond, the obligee may be the general contractor. A payment bond also protects qualifying claimants, so the project owner is not the only relevant beneficiary.

The General Indemnity Agreement, often called the GIA, is another contract. It may create reimbursement, collateral, and other obligations for the principal and additional signers. Buying a bond does not mean the surety will necessarily absorb a loss without recourse.

  • Read the executed bond and riders, not only the certificate or proposal.
  • Confirm the named parties, protected claimants, bond amount, and project.
  • Review the contract and GIA as well as the bond.

Sources: FAR 28.001: Bond, bid guarantee, and bond-type definitions · Virginia Code § 2.2-4337: Public performance and payment bonds · Fidelity & Deposit Co. v. Bristol Steel & Iron Works, Inc., 722 F.2d 1160 (4th Cir. 1983): Contractual indemnity

A construction bond connects a principal, an obligee, and a surety. The underlying contract and bond serve different roles, while a separate indemnity agreement governs obligations of its signers to the surety.THREE PARTIES. SEPARATE OBLIGATIONS.ObligeeOften the owner orupstream contractorContractBondPrincipalBonded contractorSuretyBond issuerThe GIA is a separate contract.It sets obligations owed to the suretyby the principal and other indemnitors.
A simplified construction-bond relationship. Payment-bond beneficiaries and additional indemnitors require their own review; the GIA does not give every signer identical obligations.

Bid bond

Supports the bidder’s commitment to honor the bid and furnish the required contract documents and bonds after award.

Performance bond

Secures the bonded contractor’s performance obligations, subject to the bond, incorporated contract, and applicable law.

Payment bond

Protects qualifying labor and material claimants. Eligibility, notice, proof, and suit requirements must be checked.

Sources: FAR 28.001: Bond, bid guarantee, and bond-type definitions

For unpaid subcontractors and suppliers

A payment claim starts with the bond and the work you can prove.

You may have already sent invoices, made calls, and been told payment is coming. A bond review adds a different question: what must happen now to preserve a viable claim against the right parties?

Find the governing bond

Obtain the executed payment bond and riders. Confirm the bonded contractor, surety, project, and governing statutory or contractual framework.

Trace the contracting chain

Identify who hired whom and whether the claim falls within the protected class. Federal Miller Act tiers cannot be assumed to match every state or private bond.

Support the unpaid balance

Connect labor, materials, approved changes, and invoices to the project. Account for payments, credits, releases, retainage, and disputed backcharges.

Preserve each required step

Check notice content, recipients, delivery method, waiting periods, and filing dates. An insurer-style claim submission is not a substitute for the required legal process.

Sources: 40 U.S.C. § 3133: Miller Act payment-bond rights and deadlines · Virginia Code § 2.2-4341: Payment-bond actions, notice, and waivers · Clifford F. MacEvoy Co. v. United States ex rel. Calvin Tomkins Co., 322 U.S. 102 (1944): Miller Act claimant eligibility

Need a copy of the bond? Ask the bonded contractor and awarding owner or agency. Federal law and applicable contract clauses provide copy-request procedures; Virginia public bonds are filed with the awarding public body or its designee. Read the bond-copy question

Sources: FAR 52.228-12: Prospective subcontractor requests for payment bonds · 40 U.S.C. § 3133: Miller Act payment-bond rights and deadlines · Virginia Code § 2.2-4337: Public performance and payment bonds

Miller Act and Virginia public-bond claims

Notice, the right to sue, and the filing deadline are separate checks.

A federal Miller Act claim and a Virginia public payment-bond claim can both involve ninety-day and one-year periods, but that does not make their procedures identical. Your contracting relationship, last qualifying work or delivery, and the amount claimed matter.

First identify the awarding agency and the applicable bond. A private bond, a project in another state, or a differently structured transaction needs its own review. A job’s location or funding source alone does not answer which law controls.

  • Keep evidence of the actual last labor or materials for the claim.
  • Distinguish required notice from correspondence with the surety.
  • Check the lawsuit deadline while the claim is being investigated.

Sources: 40 U.S.C. § 3133: Miller Act payment-bond rights and deadlines · Virginia Code § 2.2-4341: Payment-bond actions, notice, and waivers

Three separate timing questions for bond claims: when notice is due, when suit becomes available, and when suit must be filed. The governing law and claimant relationship determine the answers.THREE QUESTIONS. THREE TIMING CHECKS.01When is notice due?Check recipient, content, delivery method,claimant relationship, and triggering date.02When can suit begin?A statutory waiting period may apply.It does not erase a notice requirement.03When must suit be filed?Check the separate filing deadline.A claim file is not a filed lawsuit.Identify the legal rule before counting days.
An organizing framework, not a deadline calculator. The bond, governing law, claimant relationship, work history, and applicable exceptions determine the dates.
Selected public payment-bond rules. Review the statute and facts before relying on a date.
QuestionFederal Miller Act
40 U.S.C. § 3133
Virginia public bond
Va. Code § 2.2-4341
When is notice required?A qualifying claimant contracting with a first-tier subcontractor, but not the bonded prime, must notify the prime within 90 days of its last labor or materials for the claim.Subsection B generally requires a claimant contracting with a subcontractor, but not the bonded contractor, to give the contractor written notice within 90 days. Review the retainage exception.
How is notice served?Use a statutory method, including one providing written, third-party verification of delivery to the contractor. Required content also matters.Subsection B specifies registered or certified mail, postage prepaid, to the contractor’s regularly maintained business office, with the required content.
When does suit become available?An eligible claimant remaining unpaid after the statutory 90-day period may sue, subject to applicable notice and other requirements.Subsection A addresses direct contractor claimants remaining unpaid after 90 days. For other claimants, review subsection B and the applicable requirements.
When must suit be filed?No later than one year after the claimant’s last labor or materials, as provided in § 3133(b)(4).Within one year after the claimant’s last labor or materials under subsection C.

Sources: 40 U.S.C. § 3133: Miller Act payment-bond rights and deadlines · Virginia Code § 2.2-4341: Payment-bond actions, notice, and waivers · Clifford F. MacEvoy Co. v. United States ex rel. Calvin Tomkins Co., 322 U.S. 102 (1944): Miller Act claimant eligibility

Last qualifying work

The last invoice is not automatically the starting date.

For federal Miller Act timing, work needed to complete the original undertaking differs from later correction or repair. Do not assume a warranty visit or punch-list label restarts the clock. Preserve the actual work and delivery history.

Read the last-work question

Sources: United States ex rel. Noland Co. v. Andrews, 406 F.2d 790 (4th Cir. 1969): Last furnishing versus correction or repair · 40 U.S.C. § 3133: Miller Act payment-bond rights and deadlines

Negotiation does not automatically preserve the right to sue. Keep notice and filing dates under review while the surety investigates or the parties discuss payment. A consultation request does not pause those dates.

General Indemnity Agreement review

The document behind the bond can create obligations of its own.

The GIA deserves attention before signing and again when a claim arrives. It may address far more than repayment after a final judgment, and its actual language can shape the response.

Who is obligated?

Identify companies, owners, and other signers; their signing capacities; joint obligations if stated; and the bonds covered.

What can be demanded?

Review covered loss, costs, expenses, fees, collateral triggers, and the supporting records for a requested amount.

Who controls claims?

Examine settlement discretion, defense rights, evidentiary provisions, assignments, and any power-of-attorney language.

What information is required?

Review financial disclosures, books-and-records access, cooperation, and notice obligations.

What continues?

Check future-bond provisions, ownership changes, completion, cancellation, and continuing exposure.

How can obligations end?

Identify the agreement’s release or termination process, affected bonds, and any written consent required.

Sources: Bell BCI Co. v. Old Dominion Demolition Corp., 294 F. Supp. 2d 807 (E.D. Va. 2003): Indemnity and settlement authority · Fidelity & Deposit Co. v. Bristol Steel & Iron Works, Inc., 722 F.2d 1160 (4th Cir. 1983): Contractual indemnity

Personal exposure requires a signature and obligation review. Do not assume a company signature and an individual indemnity promise have the same effect, or that marriage alone makes a spouse an indemnitor. Review the actual undertaking and any asset-enforcement questions separately. Read about personal indemnity

Collateral and reimbursement demands

Identify what the surety is asking for, and why.

A demand to secure potential exposure is different from a bill for losses already paid. Depending on the GIA, collateral may be sought before the underlying dispute has been finally resolved. The trigger, requested amount, permitted use, and conditions for release need careful review.

For reimbursement, connect each requested amount to the agreement and supporting records. Review claim payments, completion expenses, professional fees, credits, recoveries, and the surety’s settlement authority. Disputing the original claim does not automatically defeat a separate indemnity obligation.

  • Separate bond liability from the GIA obligation being asserted.
  • Ask what evidence supports the demand and its calculation.
  • Identify response dates, court requests, and practical resolution options.

Sources: Bell BCI Co. v. Old Dominion Demolition Corp., 294 F. Supp. 2d 807 (E.D. Va. 2003): Indemnity and settlement authority · Fidelity & Deposit Co. v. Bristol Steel & Iron Works, Inc., 722 F.2d 1160 (4th Cir. 1983): Contractual indemnity

A bond claim alleges an unpaid amount or failure; collateral secures exposure under an agreement; reimbursement seeks repayment of covered loss and expenses. These demands have different triggers and proof requirements.IDENTIFY WHAT THE DEMAND SEEKSBond claimAn alleged unpaid amount or failureunder the bonded obligation.CollateralSecurity against exposure, if theagreement and legal requirements allow.ReimbursementRepayment of covered loss and expenses,supported under the governing agreement.Different triggers. Different proof.
These categories may overlap, but they are not an automatic sequence. Each demand requires review of its contractual or legal basis and supporting facts.

When a claim arrives

A clear record helps you answer the actual allegation.

Preserve the notices, contract, GIA, financial records, project communications, and payment history. Identify whether you are responding as contractor, obligee, indemnitor, or another participant before making admissions or agreeing to terms.

Responding to a bond claim

Performance-bond default and completion

Before a takeover, understand the trigger and the unfinished work.

A struggling project needs a practical completion plan and a legally supported response. A default declaration alone does not answer every bond condition.

01Notice and contractual conditions

What must happen first?

Review the alleged failure, required notices, cure opportunities, termination steps, and conditions that govern the surety’s obligation.

02Scope, cost, and contract funds

What remains to be done?

Document the remaining work, schedule, completion estimate, disputed changes, site conditions, and unpaid contract balance.

03Completion or another response

Which options are available?

Assess the options permitted by the bond and law, including a negotiated completion arrangement, a surety response, or litigation where needed.

Planning for the next bonded project

Coordinate the legal documents with the underwriting picture.

A business may need to address an open claim, a proposed ownership change, or an unfamiliar indemnity package before its next bid. Legal review helps connect those questions to the business’s plans.

Consider available small-business programs.

The SBA Surety Bond Guarantee program may help eligible small businesses obtain contract bonds from participating sureties. Program eligibility and the surety’s evaluation still apply.

Review the proposed bond and indemnity documents alongside any program application. A government guarantee should not be treated as eliminating the contractor’s own obligations.

SBA bond-program questions

Sources: U.S. Small Business Administration: Surety Bond Guarantee program · Fidelity & Deposit Co. v. Bristol Steel & Iron Works, Inc., 722 F.2d 1160 (4th Cir. 1983): Contractual indemnity

Prepare for the first conversation

Bring the bond, the agreement, and the project record.

You do not need a perfect file before seeking advice. These materials help explain the issue and identify what needs attention first.

Bond documentsWhat protection was issued?
Bring executed bid, performance, or payment bonds, riders, powers of attorney, the bond number, named parties, and any proposed replacement or additional coverage.
IndemnityWho signed, and what was promised?
Bring every GIA, amendment, signature page, release, and document changing the indemnitors or covered bonding program.
Project agreementsWhat work and procedures were required?
Gather the prime contract, relevant subcontracts, purchase orders, scope, specifications, change orders, and notice, cure, or termination provisions.
Work and paymentWhat was supplied, paid, or disputed?
Collect daily reports, delivery tickets, invoices, payment applications, credits, releases, retainage details, backcharges, and remaining-work estimates.
Notices and datesWhat was sent, received, and delivered?
Preserve claims, demands, default notices, delivery confirmations, mailing records, last-work evidence, and any lawsuit or hearing papers.
Goals and business impactWhat result does the business need?
Identify your goal, immediate cash-flow or completion concern, upcoming bid dates, and the parties involved. Ask how to provide sensitive records securely.

Working with Shin Law Office

Keep the legal strategy connected to the project.

A bond dispute can affect cash flow, working relationships, and the next job. We help you understand the legal position, the missing evidence, and how each proposed step relates to your goals.

  1. Identify role and dates

    Confirm the bond, parties, project type, key notices, last-work facts, and any immediate response requirement.

  2. Review the documents

    Read the bond, contract, and GIA together; assess the obligation, claim conditions, and available evidence.

  3. Build the next step

    Discuss the purpose and scope of a notice, claim submission, response, negotiation, or court action.

  4. Resolve and document

    Address settlement, completion, collateral, reimbursement, or litigation and the documents needed to implement the result.
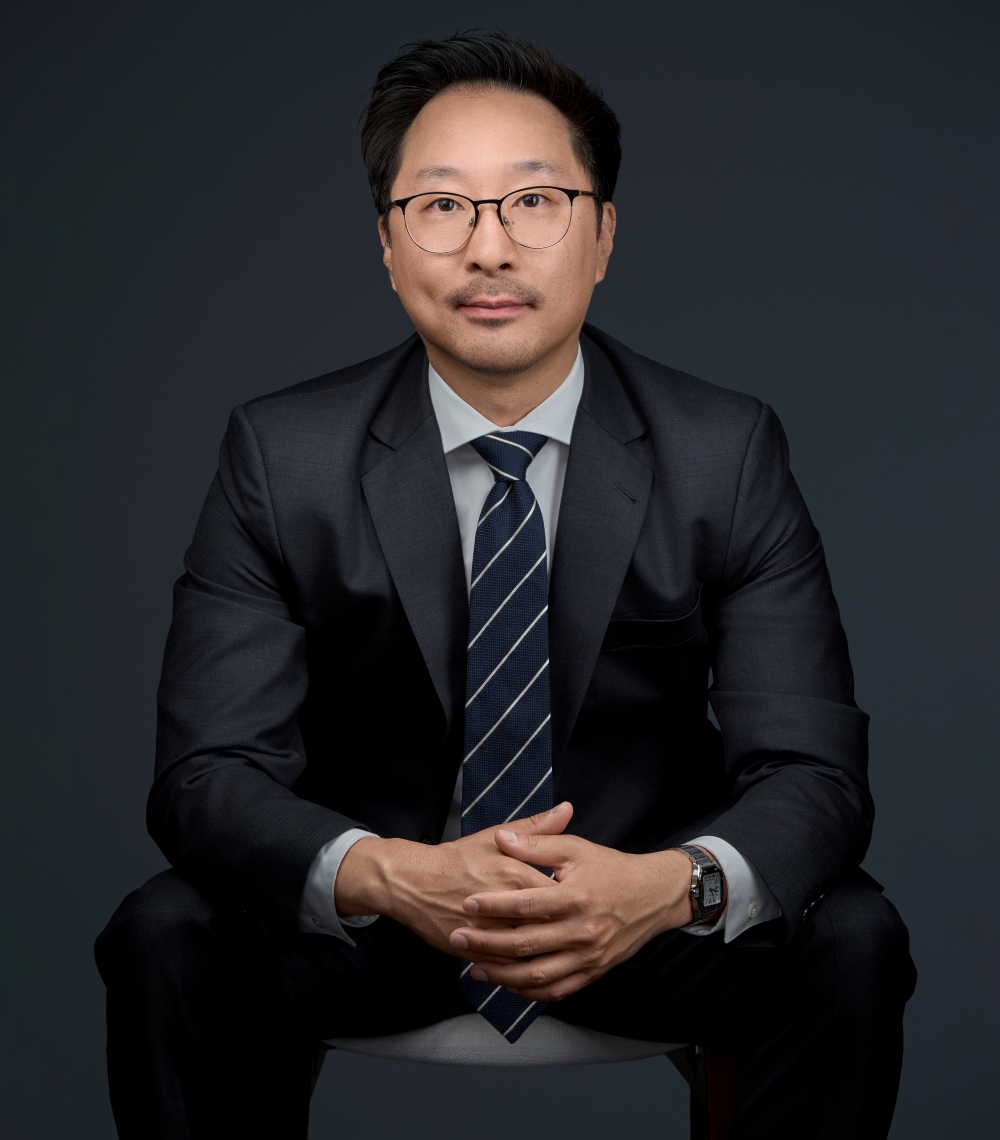
Anthony I. Shin, Esq., attorney at Shin Law Office

Meet the attorney

Anthony I. Shin, Esq.

A surety matter rarely stops at the bond form. The underlying project, the indemnity agreement, and the business consequences all deserve attention when deciding how to proceed.

Learn more about Anthony Shin

Northern Virginia counsel

Offices in Leesburg and Fairfax.

Contact Shin Law Office about a construction bond, payment claim, GIA, or surety demand. Tell us where the project is located, who awarded the contract, your role, and any upcoming date requiring attention.

Request a consultation

Office: 571-445-6565 · Cell: 571-215-8823 · Fax: 703-442-8938

Answers before you call

Surety questions, in plain language.

Start with a direct answer, then review how the bond, GIA, project, and applicable law affect your situation.

Discuss your bond matter
What is a surety bond?
A surety bond is a written undertaking that backs a principal’s obligation to an obligee, subject to the bond’s terms and applicable law. In construction, the principal is often the bonded contractor, the obligee is often the owner or upstream contractor, and the surety issues the bond. A payment bond also protects qualifying labor and material claimants. The actual parties and protection must be identified from the bond.
Is a surety bond the same as liability insurance?
No. A construction surety bond backs specified obligations to others; it is not a substitute for the contractor’s liability insurance. The surety may seek reimbursement or other relief from the principal and contractual indemnitors after a claim, subject to the governing agreement and law. Paying the bond premium does not automatically cap the contractor’s exposure at that premium.
What is the difference between bid, performance, and payment bonds?
A bid bond supports the bidder’s commitment to honor the bid and provide the required contract documents and bonds if awarded the work. A performance bond secures the bonded contractor’s performance obligations. A payment bond protects qualifying claimants supplying labor or materials. The bond form, incorporated contract, claimant eligibility, conditions, and applicable law determine the particular rights and remedies.
Who are the principal, obligee, surety, and indemnitor?
The principal is the party whose obligation is bonded. The obligee is the party to whom the bond obligation runs. The surety issues the bond. An indemnitor separately promises obligations to the surety, usually in a general indemnity agreement. The principal may also be an indemnitor, and additional companies or individuals may sign as indemnitors. A subcontractor’s bond may name the general contractor as obligee, so the owner is not always the named obligee.
What is a General Indemnity Agreement, or GIA?
A GIA is a contract governing obligations owed to the surety. Depending on its wording, it may address reimbursement, expenses, collateral, claim settlement, financial records, assignments, and continuing coverage of bonds. Review every signer, the capacity in which each signs, and the obligations covered. The GIA must be read alongside the bond and underlying contract because each document serves a different purpose.
Can signing a GIA create personal or spousal exposure?
An individual who undertakes personal indemnity may face personal contractual liability, even when the bonded work is performed through a company. Review the actual signatures, capacity, scope, and applicable law. A spouse’s liability is not established merely by the marital relationship; determine what that person signed or otherwise legally undertook. Questions about particular assets, ownership, exemptions, or enforcement require separate review.
Can the surety settle a claim without my approval?
The GIA may grant the surety broad authority to pay, defend, compromise, or settle claims, sometimes including assigned contract rights. Your disagreement with the underlying claim does not automatically remove that authority. Review the trigger, settlement language, evidence, and any applicable good-faith obligations or defenses. In Bell BCI, the court enforced the settlement and assignment authority provided by the particular agreement.
Does the bond’s penal sum cap everything I might owe?
Do not assume that it does. The penal sum states the bond amount, while the GIA may separately address reimbursement, costs, expenses, multiple bonds, and other obligations. The scope of an indemnitor’s exposure requires review of the agreement, payments, bond limits, and applicable law. A limit on one bond is not automatically a universal cap on all related contractual obligations.
I was not paid on a bonded project. Where do I start?
Obtain the payment bond and identify the project owner, bonded contractor, surety, and party that hired you. Document the labor or materials, amount unpaid, payments and credits, and last qualifying furnishing date. Then determine claimant eligibility, required notices, and the filing deadline. Sending documents to the surety may start a claim review, but it does not automatically satisfy notice to another required recipient or preserve the right to sue.
How can I obtain a copy of a payment bond?
Ask the bonded contractor and awarding owner or agency for the executed bond and riders. For federal work, FAR 52.228-12 provides a copy-request mechanism for prospective subcontractors or suppliers when the clause applies. Under 40 U.S.C. § 3133(a), a qualifying applicant can request certified copies from the contracting agency with the required affidavit. Virginia public bonds are filed with the awarding public body or its designated office or official.
How do the Miller Act, Virginia Little Miller Act, and private bonds differ?
The federal Miller Act governs qualifying federal construction payment bonds. Virginia’s public procurement bond statutes, often called its Little Miller Act, govern applicable Virginia public-project bonds. A private project bond requires review of its own terms and applicable law. Identify the actual contracting agency, project, bond, and claimant relationship. A Northern Virginia job site or a source of federal funding alone does not establish that the federal Miller Act governs.
Who must give the federal Miller Act ninety-day notice?
A qualifying claimant with a direct contract with a first-tier subcontractor but no express or implied contract with the bonded prime contractor must give the prime written notice within ninety days of its last labor or materials for which the claim is made. The notice must substantially identify the amount and the party for whom the work or supply was provided. Statutory service requirements apply. Claimants dealing directly with the prime are differently situated. More remote tiers and suppliers to ordinary material suppliers are not automatically protected.
When can a federal Miller Act payment-bond lawsuit be filed?
Section 3133(b)(1) permits suit for an eligible claimant remaining unpaid after the statutory ninety-day period following its last labor or materials for the claim. Section 3133(b)(4) requires suit no later than one year after the claimant’s last labor or materials. The separate ninety-day notice rule may also apply based on contracting tier. The statute specifies a federal-court action in the name of the United States for the claimant’s use, in a district where the contract was to be performed and executed; forum issues should be reviewed.
What are the main Virginia public payment-bond deadlines?
Virginia Code § 2.2-4341(A) addresses a direct contractor claimant remaining unpaid after ninety days from its last labor or materials for the claim. Subsection B requires qualifying claimants who contracted with a subcontractor but not the bonded contractor to give the contractor written notice within ninety days, using the specified content and registered or certified mail procedure. Subsection C requires suit within one year after the claimant’s last labor or materials. Subsection B has a retainage exception that should be reviewed separately.
Does Virginia’s retainage exception extend every bond-claim deadline?
No. Section 2.2-4341(B) excludes qualifying retainage claims from the time limitations stated in that subsection. It does not say that the separate one-year lawsuit period in subsection C disappears. Separate retainage from ordinary unpaid invoices and have both notice and filing requirements reviewed. Do not import this Virginia exception into a federal or private bond without an independent legal basis.
Is an email to the surety enough notice?
Do not assume so. The required recipient may be the bonded contractor rather than only the surety. The federal Miller Act specifies service methods including a means providing written third-party verification of delivery. Virginia § 2.2-4341(B) specifies registered or certified mail, postage prepaid, to the contractor’s regularly maintained business office. The content, recipient, method, and timing all matter. Preserve proof of service and review any additional bond requirements.
Does later punch-list or warranty work restart the bond deadline?
Not automatically. For federal Miller Act timing, the nature of the work matters. In Noland, the Fourth Circuit distinguished work required to complete the original contract from correction or repair following inspection. The invoice date, a visit to the site, or the label punch list does not alone answer the question. Identify the actual labor or materials and why they were furnished before calculating a deadline.
Can I sign away the right to sue on a public payment bond?
Federal § 3133(c) and Virginia § 2.2-4341(D) impose conditions on waivers: they must be written, signed by the person whose right is waived, and executed after that person has furnished the labor or materials specified by the statute. A later release or payment document may still affect rights. Review the exact waiver, scope, timing, payment status, and governing law before signing; the statutes do not make every release invalid.
What should I do when a bond claim is filed against my company?
Preserve the bond, GIA, underlying contract, claim papers, project records, payment history, and communications. Record receipt dates and identify any lawsuit or response deadline. Compare the claim with the work, approved changes, credits, releases, and asserted deficiencies. Review cooperation and document obligations, settlement authority, and the response strategy before making admissions or agreeing to payment. A consultation request does not extend a deadline.
Can the surety demand collateral before paying a claim?
A GIA may require collateral before the surety has paid or finally resolved the underlying exposure. Whether a demand is enforceable, when it is triggered, and how much is supportable depend on the contract, facts, and applicable law. Review the clause, demand, claims, reserve explanation, and supporting records promptly. A collateral dispute may involve a request for court-ordered performance as well as a later money claim.
How is collateral different from reimbursement?
Collateral is security requested or held against exposure under the applicable agreement. Reimbursement seeks repayment of losses or expenses already incurred or paid as covered by that agreement. They may arise at different times and involve different proof. Review how collateral can be used, how payments are credited, and what conditions govern an accounting, reduction, or return of any remaining security.
Does declaring contractor default automatically trigger a performance-bond payment?
No. The bond, incorporated contract, notice and cure provisions, termination requirements, and available surety response options need review. An unsupported or procedurally defective default can create additional disputes. If completion is needed, document the remaining scope, schedule, estimated cost, and unpaid contract balance. Federal takeover agreements have their own framework; private and other public bonds may use different procedures.
Can change orders, ownership changes, or an assignment affect bonding?
They can require review of notice, consent, additional coverage, indemnitors, and continuing obligations. Do not assume that every change releases the surety or that every change is automatically covered. Read the bond, GIA, contract, and proposed transaction together. Federal rules address consent of surety and additional bond coverage; other projects and bonding programs require their own analysis.
Can I dispute the surety’s reimbursement calculation or legal expenses?
Review the contractual basis and supporting records for each requested amount, including claim payments, completion costs, expenses, credits, recoveries, and fees. The GIA may give the surety substantial settlement discretion or evidentiary rights. A disagreement about the original claim is not always enough to defeat indemnity. Available defenses, including any issue involving the agreement’s scope or applicable good-faith standard, require a fact-specific review.
Do private payment bonds use the same deadlines as public-project bonds?
Not necessarily. A private bond can have its own claimant definition, notice requirements, claim procedure, suit limitation, and incorporated contract terms, subject to applicable law. Review the executed form and riders. A familiar label such as payment bond does not justify applying the federal or Virginia public-project timetable to every private job.
Can a lawyer increase my bonding capacity or issue a bond?
Bond issuance and capacity are underwriting decisions made by the surety, usually working through a surety agent or broker. Legal work can address agreements, indemnity terms, ownership changes, claims, and documentation that affect the relationship. Coordinate that work with accurate financial and operational information from the business and its advisers. No legal review guarantees approval or a higher limit.
Could the SBA Surety Bond Guarantee program help my business?
Potentially. SBA guarantees certain bonds issued by participating sureties for eligible small businesses that may have difficulty obtaining conventional bonding. The program can support contract bonds, but eligibility, project requirements, and the surety’s evaluation still apply. An SBA guarantee is not automatic approval and should not be treated as a release from the contractor’s bond or indemnity obligations. Review the current program with a participating agent and the proposed documents with counsel.
What should I bring to a surety consultation?
Bring the executed bonds and riders, GIA and amendments, prime contract and relevant subcontracts, claims or demands, notices and delivery records, payment history, and a short project timeline. Identify the last work or delivery dates, amount disputed, unpaid retainage, default or termination events, and any court deadline. For an upcoming bond, bring the solicitation and proposed documents. Ask how to share sensitive financial and project records securely.

Before you sign, or when a claim arrives.

Bring the bond, the project details, and the demand or decision you need help with. We can review the obligations, discuss the available options, and identify the next step.

Mention notice dates, last work or delivery, bid deadlines, default notices, and any court response requirement.
Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.

Copyright © 2026 Shin Law Office, PLC. All rights reserved.

Powered by HILARTECH, LLC

Copyright © 2026 Shin Law Office, PLC. All rights reserved.

Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.