Shin Law Office · Executors, beneficiaries & families

Probate Administration Attorneys in Northern Virginia

You have enough to carry. We help with what comes next.

After a loss, the bank may ask for authority, family members may ask for answers, and the estate may come with deadlines you have never faced. Led by Adam L. Engel, Esq., our probate practice helps you understand the responsibilities, organize the records, and take the next step with a clear plan.

Already qualified or received court papers? Bring the appointment documents, notices, and any upcoming filing or hearing date.

Executor & administrator counselInventory & accounting supportEstate & trust disputes

What does a probate administration attorney help with?

Determining who can act for the estate, which assets need administration, what notices and filings are required, how debts and distributions should be handled, and how to respond to a dispute. Shin Law Office assists executors, administrators, beneficiaries, and families with the legal questions that arise after a death.

Starting an estateReview the will, court, authority, assets, and available procedures.
Managing the responsibilityConnect deadlines and decisions to records, duties, and beneficiary rights.

You do not need every answer before you call

Begin with the person, the documents, and the next decision.

A person named executor may be unsure whether they can act yet. A beneficiary may be waiting for information. A family may agree on the goal but disagree about a house, a debt, or a distribution. Start by identifying your role and what needs attention.

Before making an estate decision

  • Locate the original will, trust documents, and any appointment papers.
  • Identify how assets are titled and whether beneficiaries are named.
  • Preserve financial records and confirm authority before moving money.
  • Flag an urgent expense, planned sale, dispute, or court date.

Probate administration & related services

Find help for the estate, the responsibility, or the dispute.

Explore 11 services, from the first probate question to estate accounting, contested matters, and planning. Guardianship and conservatorship address the needs of a living person and follow a separate process.

Planning for your own family? Coordinate the will, trusts, powers of attorney, beneficiary designations, and ownership arrangements before they are needed.

Explore estate planning

One family, several possible transfer routes

Start with who owns each asset and how it is meant to pass.

A bank account in one person’s name, an account with a valid beneficiary, a jointly owned property, and an asset properly held in a trust can follow different rules. The will is important, but it is not the only document that matters.

We help identify which assets require estate administration and which may transfer under another arrangement. We also review reporting, creditor, tax, and practical issues that can remain even when an asset passes outside probate.

Assets that may pass outside probate

Sources: Virginia Code § 64.2-1300: inventory and values · Virginia Code § 64.2-628: transfer-on-death deed requirements · Virginia Code § 64.2-634: claims against TOD property

Asset ownership and transfer instructions determine the estate, beneficiary, or trust routeSole-name assetsEstate processNamed beneficiaryDirect transferFunded trustTrust processPersonal propertyReview authorityValid designationReview claim stepsTrust-owned assetsReview trust terms
Illustrative routes. Sole-name personal assets without an effective transfer arrangement may require estate administration or an applicable shortcut. Title, valid documents, and the facts determine the actual route.
$75,000

Small-estate affidavit threshold

Entire personal probate estate, wherever located, valued at death.

Current Virginia law provides an affidavit procedure when the statutory conditions are met. These include at least 60 days since death, no pending or granted personal-representative appointment in any jurisdiction, and probate of any will.

The amount is only one requirement. Review all known successors, entitlement, and the prescribed affidavit. This procedure does not transfer real estate.

Review the complete small-estate question

Sources: Virginia Code § 64.2-601: small-estate affidavit

A calendar tied to the correct event

Different filings. Different recipients. Different starting points.

Qualification is the formal appointment process for a personal representative. Admission of a will to probate is a separate event. The distinction matters because notice requirements can arise even when no personal representative qualifies.

For an ordinary decedent’s estate requiring these filings, notice, the notice affidavit, the inventory, and the first account each have a purpose. Confirm which duties apply and keep the papers showing when the relevant event occurred.

Sources: Virginia Code § 64.2-508: notice and affidavit · Virginia Code § 64.2-1300: inventory and values · Virginia Code § 64.2-1304: personal representative accounts

Three ordinary probate filing checkpoints: notice, inventory and affidavit, and first account30416daysmonthsmonthsRequired noticeTwo separate filingsFirst estate accountTo entitled recipientsInventory + notice affidavitGenerally covers 12 months
General checkpoints, subject to exceptions and orders. Notice generally runs from qualification or admission of the will; inventory and the first estate account generally run from qualification. These are not universal deadlines for trusts, curators, or conservators.
Have a missed date or a court notice? Bring it to counsel promptly. A consultation request, family discussion, or pending document request does not automatically extend a filing period.

Make the file easier to understand

Good records explain both what exists and what happened to it.

An inventory identifies required assets and values. An account explains the money and property received, paid, distributed, or remaining. Begin organizing the supporting records before the first filing is due.

AuthorityWho is authorized to act?
Gather the original will and codicils, death certificate, trust documents, qualification certificate, bond papers, and any court orders. Identify who has already acted and in which capacity.
PeopleWho may have rights or responsibilities?
List the spouse, family relationships, heirs, beneficiaries, fiduciaries, and relevant contact details. Explain disagreements and identify any minor or person needing assistance.
AssetsWhat exists, and how is it owned?
Bring deeds, account statements, beneficiary designations, business records, vehicle titles, and a list of personal property. Note assets elsewhere, digital records, and any property that cannot be located.
ValuesWhat records support the inventory?
Keep date-of-death balances, investment information, appraisal reports, and evidence of ownership. Identify property that may need a qualified valuation before filing, sale, or distribution.
Money movementWhat has come in or gone out?
Organize complete statements, receipts, checks, invoices, sale records, and distributions. Keep estate funds and personal funds separate, and document the basis for expenses and reimbursements.
Dates and concernsWhat needs attention next?
Bring notices, creditor demands, Commissioner correspondence, prior accounts, hearing information, and signed orders. Flag a planned transaction, threatened loss, disputed will, or request for review.
A missing record is a question to address, not a reason to guess. Tell us what is unavailable, which institution or person holds it, and what efforts have already been made to obtain it. Ask how to share sensitive financial documents securely.

Before paying or distributing

The money in the account may not all be available to inherit.

Debts, taxes, administration expenses, statutory rights, and unresolved claims can affect what may be distributed. If the estate cannot pay everything, payment priority becomes especially important.

We help review the obligations, supporting records, available procedures, and reserves before a proposed payment or distribution. The goal is a decision that can be explained and documented under the rules that apply.

Creditor claims & insolvent estates

Sources: Virginia Code § 64.2-528: debt payment priority · Virginia Code § 64.2-556: distribution safeguards

Review assets, claims, taxes, and recipients before an estate distributionDistribution reviewAssetsClaimsTaxesRecipientsTitle, authority,and valueDebts, expenses,and prioritiesReturns, payments,and reservesRights, shares,and records
A distribution review connects ownership, obligations, taxes, and recipient rights. No single balance, family agreement, or elapsed period resolves every estate’s remaining duties.

Real estate and other jurisdictions

Confirm authority before a sale.

Review the deed, will, liens, ownership interests, and any court requirements. Out-of-state property may require coordination with local counsel and a separate procedure.

Selling inherited property
Property in another state

When administration becomes contested

Identify the disagreement before choosing the legal response.

A challenge to a will, a request for trustee information, and an allegation that funds were misused raise different questions. Start with the document, the duty, the evidence, and the relief being sought.

A disputed will

Review the signing circumstances, capacity, influence, execution, standing, and prior probate proceedings. An unequal inheritance alone does not establish an invalid will.

Will contests

A fiduciary or trust concern

Connect the requested information or disputed transaction to the governing document and legal duty. Assess remedies and defenses based on the record.

Fiduciary litigation
Trust disputes

A ruling already entered

The decision-maker, signed order, entry date, and procedural history determine the review route. Clerk appeals and will contests use different rules.

Probate appeals

Send the complete signed order and the date entered when requesting review. Do not use the timing rule for one type of probate challenge as the deadline for another. Read about the different routes.

Working with Shin Law Office

A manageable sequence of decisions, records, and next steps.

The appropriate scope may be targeted advice, help with filings and accounts, ongoing estate administration counsel, or representation in a dispute. We begin by clarifying who the client is and what the matter requires.

  1. Understand the matter

    Identify the client, parties, documents, assets, court, immediate concerns, proposed scope, and fees.

  2. Map the duties

    Review authority, transfer routes, notices, filings, financial records, and decisions that need attention.

  3. Carry out the work

    Prepare agreed filings, review transactions and claims, coordinate needed information, and address disputes.

  4. Plan the next stage

    Assess remaining obligations, accounts, tax coordination, distribution records, and any further court steps.
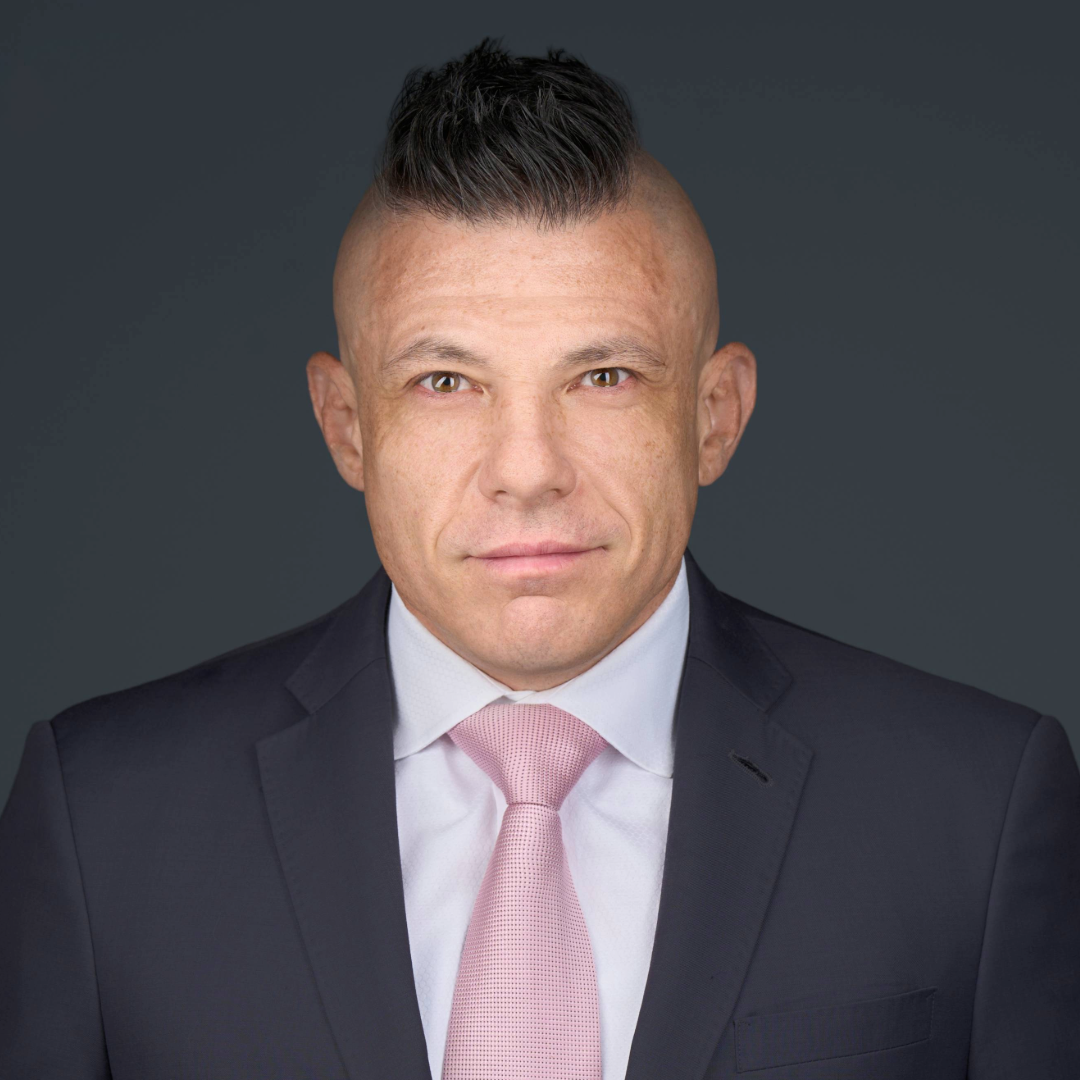
Adam L. Engel, Esq., estate planning and probate attorney at Shin Law Office

Meet your probate counsel

Adam L. Engel, Esq.

Estate Planning & Probate · Attorney, Of Counsel

Administering an estate can mean making legal and financial decisions while the family is still processing a loss. Clear explanations and an organized file help make those decisions easier to approach.

Adam leads the firm’s probate practice and assists executors, administrators, and families with estate administration. His work in estate planning, trusts, real estate, and business matters provides context when those issues intersect with an estate.

Meet Adam Engel

Probate counsel in Northern Virginia

Offices in Leesburg and Fairfax.

We assist clients across Loudoun, Fairfax, Arlington, Alexandria, Prince William, and the surrounding Northern Virginia communities.

The right probate court depends on the deceased person’s circumstances and applicable venue rules. Tell us where the person lived, where property is located, and whether a will has been admitted or a representative has already qualified.

Sources: Virginia Code § 64.2-443: probate jurisdiction

Answers before you call

Virginia probate questions, in plain language.

Start with the common question, then review the documents, ownership, family relationships, and procedural history that make the estate different.

Discuss the estate
What is probate administration in Virginia?
Probate technically concerns proving and recording a will. Estate administration is the broader work of identifying authority, collecting and protecting assets, addressing debts and taxes, keeping required accounts, and distributing property. The terms are often used together. Not every asset follows the same process, and an estate may involve probate, beneficiary transfers, and trust administration at the same time.
Does having a will mean an estate can avoid probate?
No. A will gives instructions for property it controls and may nominate an executor, but it does not by itself move every asset outside probate. Account ownership, beneficiary designations, survivorship rights, trust funding, and applicable small-estate procedures matter. Review the actual documents and each asset’s title before deciding which process is needed.
What is the difference between an executor and an administrator?
An executor is generally the person nominated in a will who qualifies to administer the estate. An administrator is appointed when administration is needed without a qualifying executor, including many estates without a will. Both are personal representatives and have fiduciary duties. The appointment, will, law, and any court orders define the person’s authority.
What should a family gather before a probate consultation?
Locate the original will and any codicils, death certificate, trusts, deeds, account statements, beneficiary information, debts, and court papers. Make a list of family members and known heirs and beneficiaries. Preserve records and secure property lawfully. Explain urgent expenses, a planned sale, a dispute, or an approaching date; you can ask for help before every document has been found.
Where is a Virginia will offered for probate?
The starting point is generally the circuit court in the county or city where the deceased person had a known place of residence. Virginia provides other venue rules when there was no known residence and a special presumption concerning residence before entry into certain care facilities. Confirm the proper locality and appointment requirements with the clerk or counsel.
Can I act because I am named executor or held a power of attorney?
Do not assume that either document alone supplies current authority to administer the estate. Being nominated as executor is different from qualifying before the clerk. A power of attorney terminates at the principal’s death, subject to statutory protections for certain good-faith actions without knowledge. Confirm the authority needed for the particular asset, bank transaction, or estate decision.
What happens if someone dies without a will?
Virginia’s intestacy rules determine who inherits property not effectively disposed of by will, subject to debts, expenses, statutory rights, and the rules governing the property. The surviving spouse does not necessarily receive everything, especially where there are descendants who are not also the spouse’s descendants. Identify the family relationships and assets before promising shares or distributing property.
Which assets may pass outside probate?
Examples can include assets with effective beneficiary designations, qualifying survivorship ownership, property properly held in a trust, and property covered by a valid transfer-on-death deed. The actual title and governing document control. An asset passing outside probate may still create tax, creditor, reporting, or administration questions. A will does not automatically override a valid beneficiary designation.
What is Virginia’s current small-estate affidavit limit?
Section 64.2-601 uses a limit of $75,000 for the deceased person’s entire personal probate estate, wherever located, valued as of death. Other conditions include at least 60 days since death, no pending or granted application to appoint a personal representative in any jurisdiction, and probate of any will. The required affidavit and successor requirements also apply. This is not a shortcut for transferring real estate.
When must heirs and beneficiaries receive notice?
Section 64.2-508 generally requires notice to specified people within 30 days after qualification or admission of the will to probate, with listed exceptions. An affidavit concerning notice is generally recorded with the clerk within four months. The notice does not mean every recipient will inherit. This notice requirement is distinct from a creditor-notice procedure.
When is the estate inventory due?
For an ordinary qualifying decedent’s estate, the inventory is generally due to the Commissioner of Accounts within four months after the order conferring authority. It identifies required assets and values; the statutory reporting categories can extend beyond the assets simply collected into an estate account. Additional assets discovered later also require attention. Confirm any applicable exception and the Commissioner’s instructions.
When is the first estate accounting due?
The ordinary rule for a personal representative is a first account within 16 months after qualification, covering the first 12 months. Later accounts follow statutory schedules, and an earlier account may be required. Special procedures or exceptions may apply. Sixteen months is not a deadline to finish every estate, and it is not the general first-account rule for every type of fiduciary.
Can an heir or beneficiary request estate records?
Section 64.2-508 gives qualifying recipients a procedure to request copies of specified filings, subject to exceptions and timing rules. A written request is generally prospective and does not automatically require delivery of every supporting voucher. Trust beneficiaries have separate information and reporting rights. Review your status, the document requested, and which person has the duty to provide it.
Should an executor pay every bill as soon as it arrives?
Not automatically. First identify the debt, supporting records, available assets, secured interests, taxes, expenses, and any applicable priority. When assets are insufficient, Virginia prescribes an order of payment and treatment of claims within the same class. Paying the most insistent creditor first, or distributing to family too early, can create problems for the estate and representative.
Does notice to creditors automatically erase unpaid debts?
No. Current § 64.2-508.1 provides an optional notice procedure with publication, delivery, claim-presentation, and affidavit requirements. Its stated timing involves the later of the statutory publication period and a period after delivery to a claimant. It has exclusions and limits on its effect, including possible remaining estate and recipient liability. Do not treat a published notice or six months of silence as universal debt cancellation.
When can beneficiaries receive a distribution?
A distribution should follow review of authority, ownership, creditor exposure, taxes, expenses, reserves, beneficiary rights, and any required court or accounting steps. Virginia provides procedures and safeguards relevant to distribution, but family agreement alone does not remove every obligation. An interim distribution may be possible in some cases; the decision depends on the estate and the remaining risks.
Can the executor sell an inherited house?
That depends on title, the will, the representative’s authority, debts, co-owners, and any court requirements. Virginia real estate does not always pass through the same administration route as a solely owned bank account. Review the deed and estate documents before signing a sale contract, distributing proceeds, or assuming the executor controls the property.
What if the person owned property in another state?
Out-of-state real property can require a separate local procedure or ancillary administration, depending on ownership and the law where it is located. Other assets may follow different transfer rules. Identify every jurisdiction, deed, appointment, and beneficiary arrangement early so the Virginia administration can be coordinated with appropriate local counsel and institutions.
How long does Virginia probate take, and what will legal help cost?
There is no single timetable or fee for every estate. Asset collection, sales, creditor issues, taxes, required accounts, missing information, and disputes affect the work. A straightforward matter may differ substantially from an insolvent or contested estate. Ask about the proposed scope, fee arrangement, court and Commissioner charges, appraisal needs, and expected stages before representation begins.
Are a final income tax return and an estate tax return the same thing?
No. The deceased person’s final individual income tax return, an estate’s income tax return, and a federal estate tax return address different obligations. Filing requirements depend on the facts and the applicable year. An estate may need its own tax identification number and records of income and distributions. Coordinate legal administration with appropriate tax advice before closing or distributing the estate.
Can a will be challenged because someone thinks it is unfair?
Disappointment alone is not a legal ground to invalidate a will. Potential issues include capacity, undue influence, fraud, or failure to satisfy execution requirements. Standing, evidence, prior proceedings, and the correct filing route matter. Section 64.2-448 provides a one-year period for certain eligible will-contest complaints, with exceptions; it is not a universal deadline for every person or probate challenge.
What if an executor or trustee is withholding information or misusing assets?
Preserve the appointment papers or trust, reports, requests for information, account records, communications, and the particular transactions at issue. A delay, an information dispute, and an unauthorized transfer can require different responses. Counsel can assess the duty, available evidence, possible accounting or court relief, and defenses. A fiduciary accused of misconduct should preserve the same records and obtain advice promptly.
Is administering a trust the same as administering a probate estate?
No. A trustee acts under the trust and applicable trust law; a personal representative administers the decedent’s estate under the relevant appointment and estate rules. The same person may hold both roles, but the authority, assets, reporting obligations, and beneficiary rights can differ. A funded trust may reduce probate while still requiring meaningful administration after death.
How is an appeal from a probate clerk’s order different from a will contest?
Under § 64.2-445, an interested person may appeal a covered clerk’s order to the circuit court within six months, where the matter is heard anew. A complaint under § 64.2-448 is a distinct will-contest procedure with its own eligibility and timing rules. Review of a circuit-court judgment follows different appellate rules. Obtain advice immediately and do not use one route’s deadline for another.
Are guardianship and conservatorship part of settling an estate after death?
They concern decision-making for a living person and are distinct from administration after death. A guardian generally addresses personal matters, while a conservator addresses financial matters within the court’s order. Virginia requires consideration of less restrictive alternatives and an appropriate evidentiary showing. A diagnosis, age, or family disagreement alone does not automatically justify removing decision-making rights.
Can probate-avoidance planning be completed after someone dies?
After death, existing titles, beneficiary designations, trusts, and valid transfer documents must be evaluated under applicable law. You cannot simply create a new planning arrangement as if the person were still living. For example, a Virginia transfer-on-death deed must satisfy legal requirements and be recorded before the transferor’s death. Probate avoidance also does not automatically eliminate creditor, tax, or family-rights issues.

You do not have to figure out the entire estate today.

Start with what you know, the papers you have, and the decision that cannot wait. Adam L. Engel, Esq. and the Shin Law Office team can help identify the appropriate next step.
Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.

Copyright © 2026 Shin Law Office, PLC. All rights reserved.

Powered by HILARTECH, LLC

Copyright © 2026 Shin Law Office, PLC. All rights reserved.

Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.