Approval & filings
Voluntary Dissolution
Review the governing documents, owner approvals, and a practical closing plan. Distinguish ending the entity from one owner leaving an otherwise continuing business.
Read the related answer
Shin Law Office · Northern Virginia
Close the business with a clear plan.
Closing a company involves more than a state filing. We help business owners address approvals, debts, assets, tax coordination, and disputes so they understand what needs to happen and which responsibilities continue.
Voluntary and disputed dissolution, LLC cancellation, and corporate winding up. Include any court date, creditor notice, or proposed asset transfer when you contact us.
Identify the entity, obtain the required authority, wind up its affairs, and complete the correct state filings. The order matters: a Virginia LLC files articles of cancellation after winding up; a Virginia stock corporation ordinarily files articles of dissolution before winding up and articles of termination afterward.
Creditor claims, taxes, contracts, guarantees, and owner distributions need separate attention. A final filing does not mean that every obligation or claim has ended.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-743: corporate articles of dissolution · Va. Code § 13.1-750: corporate articles of termination · Va. Code § 13.1-755: survival of remedies after corporate termination
Start with your situation
Choose the closest situation and the issue you need to address. The guide points to useful records and a relevant answer.
Step 1 of 2
Select your starting point.
This guide organizes a consultation. It does not determine legal authority, solvency, or whether a distribution or filing is permitted.
Six ways we help
Search using the situation in your own words, from “partner will not agree” to “personal guarantee” or “articles of cancellation.”
Try “SCC paperwork,” “split remaining assets,” “deadlock,” or “lease guarantee.” Leave out names, account numbers, and confidential details.
Showing all six topics.
Review the governing documents, owner approvals, and a practical closing plan. Distinguish ending the entity from one owner leaving an otherwise continuing business.
Read the related answerUse the right Virginia State Corporation Commission sequence. LLCs file cancellation after winding up; stock corporations ordinarily file dissolution, then termination after completion.
Read the related answerInventory debts, demands, and contingent claims. Evaluate payments, settlements, statutory notices, and provisions for liabilities before remaining assets go to owners.
Read the related answerReview asset sales, valuations, liens, member loans, capital contributions, and distribution rights. Document who receives what after the required treatment of obligations.
Read the related answerAssess owner deadlock, misconduct allegations, and judicial dissolution standards. Consider negotiated exits, buyouts, or litigation based on the entity and evidence.
Read the related answerCoordinate final taxes, payroll, leases, guarantees, licenses, and records. Identify continuing obligations and obtain any required releases or separate account closures.
Read the related answerChoose “All topics” to broaden the results, or contact the firm about the business and the unresolved issue.
Discuss your situationVirginia law · Reviewed October 3, 2026
“Dissolve the company” can describe several different legal steps. An LLC and a stock corporation do not use the same sequence or the same final document.
For a Virginia LLC, winding up must be complete before articles of cancellation are filed. For an ordinary voluntary Virginia stock corporation closing, articles of dissolution begin the formal winding-up stage, followed by articles of termination when the requirements are met.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-742: corporate dissolution authorization · Va. Code § 13.1-743: corporate articles of dissolution · Va. Code § 13.1-750: corporate articles of termination
| Question | Virginia LLC | Virginia stock corporation |
|---|---|---|
| Authority to close | Review a written dissolution event in the governing documents, unanimous written member consent, or another applicable statutory basis. | Review board and shareholder authorization, governing documents, and any applicable consent alternative. |
| Ordinary filing sequence | Complete winding up, then file articles of cancellation. | File articles of dissolution, complete winding up, then file articles of termination. |
| Before the final filing | The cancellation statement must accurately confirm that winding up is complete. | The termination filing must satisfy asset-distribution and state tax certifications, among other requirements. |
This comparison addresses ordinary voluntary closings. Court proceedings, automatic cancellation, entities formed elsewhere, and special statutory situations require a separate review.
A canceled Virginia LLC can still have unfinished affairs and surviving claims. Review the SCC status, remaining assets and obligations, and whether reinstatement or a final closing process is appropriate.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
Read the reinstatement answerWinding up & creditor claims
The bank balance is only part of the picture. A business may also have unpaid invoices, secured loans, employee compensation, tax obligations, a disputed contract, or a claim that has not yet matured.
For a Virginia LLC, completed winding up requires debts, liabilities, and obligations to be paid or discharged, or reasonably adequate provision to be made, with the remaining assets distributed. Corporate winding up and termination have their own requirements.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-745: effect of corporate dissolution · Va. Code § 13.1-750: corporate articles of termination
Virginia offers optional statutory procedures for known and other claims. The required content, exclusions, publication methods, and litigation deadlines differ. A generic letter or website announcement may not achieve the intended result.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-746: known claims against a dissolved corporation · Va. Code § 13.1-746.1: other claims and public notice
Read the notice answerPending disputes, contingent liabilities, and insurance issues can affect the closing plan. Court-approved security is available for certain claims under specified conditions. Match the provision to the actual risk and the final filing requirements.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-746.2: court-approved claim security
Read about surviving claimsAsset distribution
Review the governing rights, capital accounts, owner loans, liens, and transfer restrictions before moving company money or property.
An owner may be both a member and a creditor. Documented debt, capital contributions, and distribution rights need separate treatment. An owner loan is not automatically ahead of every other claim.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
Equipment, real estate, intellectual property, and contracts may require valuations, releases, assignments, or consent. Corporate dissolution does not itself transfer title to corporate property.
Sources: Va. Code § 13.1-745: effect of corporate dissolution
Use the applicable agreement and statutory rules to determine what owners receive. Keep a clear record of distributions and the treatment of obligations. Do not assume every closing ends in an equal split.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-750: corporate articles of termination
Judicial & disputed dissolution
Deadlock, alleged misconduct, and a desire to leave the business can raise different questions. Dissolution is one possible outcome; a negotiated owner exit may be another.
The judicial test concerns whether continuing the business under its articles and any operating agreement is reasonably practicable. Examine the business purpose, decision-making structure, and actual breakdown.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
Read the LLC answerFor nonpublic corporations, shareholder grounds include specified deadlock, illegal or oppressive conduct, fraud, and misapplied or wasted assets. Creditor proceedings have separate conditions.
Sources: Va. Code § 13.1-747: corporate judicial dissolution
Read the corporate answerA negotiated sale or buyout may let the company continue. Certain corporate dissolution cases also permit a statutory purchase election. Valuation, financing, guarantees, and deadlines need attention.
Sources: Va. Code § 13.1-749.1: purchase election in certain corporate dissolution cases
Read the buyout answerKeep governing agreements, bank and accounting records, voting history, relevant communications, and court papers. If assets may be moved or a hearing is approaching, identify that issue when contacting counsel. Do not assume an ownership interest permits taking company property or accessing another person’s accounts.
Discuss an owner disputeLiability & tax wind-down
An accepted SCC filing does not close an IRS account, release a personal guarantee, terminate a lease, or complete final payroll. Those items need their own documents, decisions, and confirmations.
Work with the accountant and payroll provider on final returns, deposits, wage reporting, benefits, and tax accounts. The legal entity and its tax classification may be different.
Sources: IRS: closing a business, final returns, payroll, and business accounts · Virginia Tax: closing your business
Review lease exits, lender consents, service contracts, insurance, and licenses. An agreement between owners does not itself release a creditor’s rights against a guarantor.
Read the guarantee answerRetain approvals, filings, financial records, notices, releases, and tax confirmations. Preserve records needed for pending or anticipated disputes and identify who receives later correspondence.
Sources: IRS: closing a business, final returns, payroll, and business accounts · Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-755: survival of remedies after corporate termination
Prepare for a useful conversation
Start with what you have. Identify missing records and who lawfully holds them; do not collect another person’s information without authorization.
How working with us begins
Identify the entity, ownership, governing documents, financial position, and immediate deadlines.
Map approvals, claims, assets, contracts, taxes, and the correct filing sequence.
Address negotiations, notices, required documents, and any owner or creditor dispute.
Verify filing certifications, record distributions, and identify the obligations and records that continue.
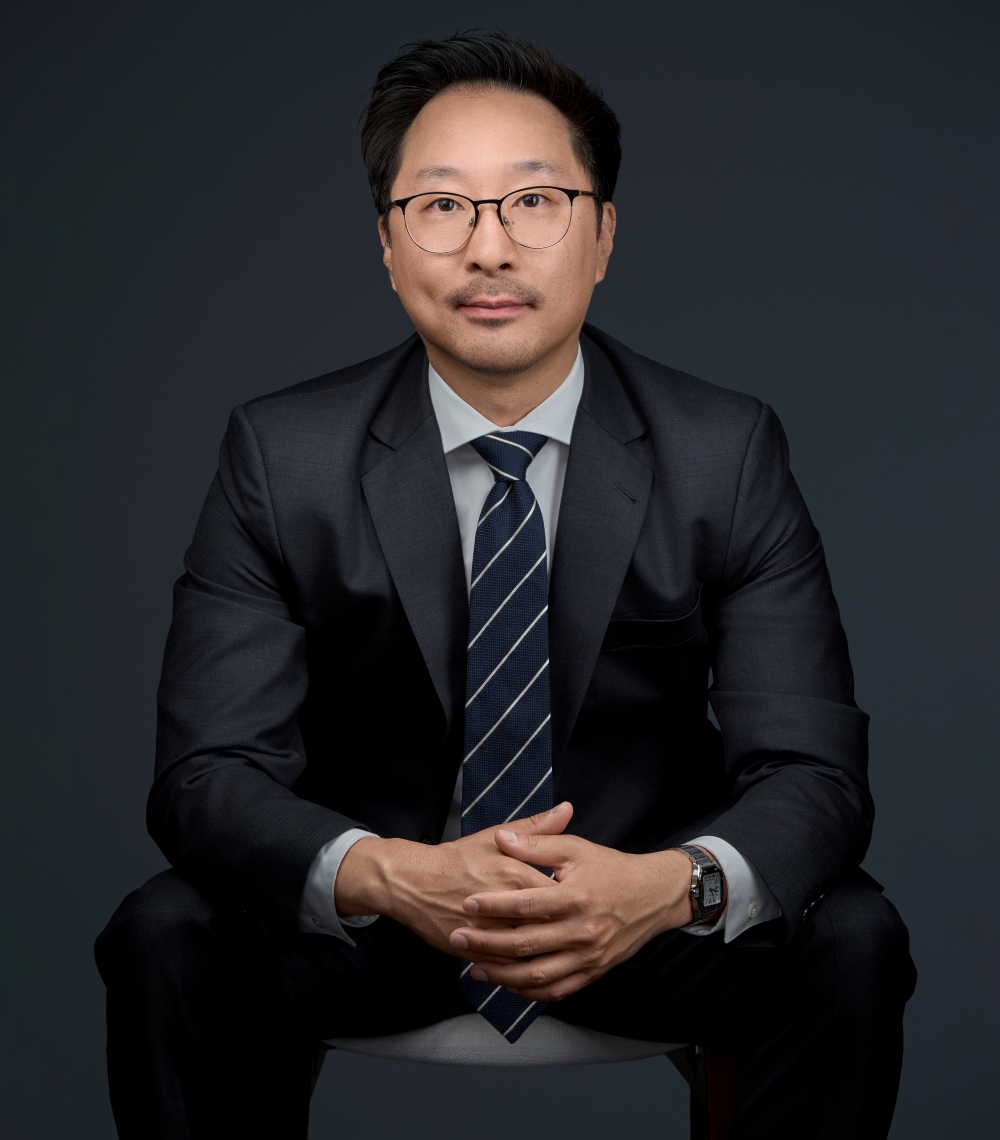
Shin Law Office
Founder
A business closing can follow retirement, a change in direction, financial pressure, or a breakdown between owners. The legal work should account for both the reason for closing and the obligations still on the books.
Shin Law Office assists with voluntary and disputed business dissolution, winding up, and related transactions and litigation. We coordinate legal issues with the business’s accounting and tax professionals. Representation follows a conflicts check and an agreed engagement.
Meet Anthony I. ShinNorthern Virginia
Shin Law Office helps Northern Virginia business owners address LLC dissolution, corporate winding up, SCC filings, owner disagreements, and the obligations connected to closing a company.
Tell us where the business was formed, who owns it, why it may be closing, and what remains unresolved. Include any creditor deadline, court date, or proposed asset transfer.
Request a consultationOffice: 571-445-6565
Cell: 571-215-8823
Fax: 703-442-8938
118 Edwards Ferry Road, N.E.
Unit 110
Leesburg, VA 20176
8300 Arlington Boulevard
#B2
Fairfax, VA 22031
Virginia business dissolution FAQs
The entity, governing documents, financial condition, and unresolved obligations determine the closing process. These answers explain common starting points.
Discuss your questionConfirm the dissolution authority in the articles of organization, operating agreement, and Virginia law. Then wind up the LLC: address debts and claims, make reasonably adequate provision where appropriate, and distribute the remaining assets. A Virginia LLC files articles of cancellation after winding up is complete. Simply stopping operations or filing a corporate dissolution form is not the same process.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
For an ordinary voluntary dissolution of a Virginia stock corporation, obtain the required board and shareholder authorization and file articles of dissolution with the State Corporation Commission. Wind up the corporation, then file articles of termination when the statutory completion requirements are met. The termination filing includes certifications about asset distribution and state tax returns and payments. Special situations can follow different procedures.
Sources: Va. Code § 13.1-742: corporate dissolution authorization · Va. Code § 13.1-743: corporate articles of dissolution · Va. Code § 13.1-750: corporate articles of termination
Dissolution begins the legal process of closing an entity. Winding up is the work of collecting assets, addressing obligations, and distributing what remains. Cancellation is the final entity filing for a Virginia LLC; termination is the final filing for a Virginia stock corporation. The filing sequence differs by entity type, and the final filing does not eliminate every surviving claim.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-745: effect of corporate dissolution · Va. Code § 13.1-750: corporate articles of termination · Va. Code § 13.1-755: survival of remedies after corporate termination
Stopping operations does not complete a legal wind-down. Annual fees, taxes, contracts, claims, and records still need attention. A Virginia LLC that is automatically canceled may still need its affairs wound up by its managers or members as trustees in liquidation. Automatic cancellation alone does not make those people personally liable, but it does not resolve the underlying obligations.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
Virginia law recognizes a dissolution event specified in writing in the articles or operating agreement, unanimous written member consent, and other statutory events. Review the actual agreement and the event being relied on before assuming that a majority vote is enough. A member who cannot obtain voluntary dissolution may need to assess whether the separate judicial dissolution standard is satisfied.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
The ordinary voluntary process requires appropriate board action and shareholder approval, subject to statutory alternatives. The default shareholder threshold in section 13.1-742 is more than two-thirds of all votes entitled to be cast, but the articles may set a different permitted threshold. Voting groups, notice, quorum, written consent, and the governing documents need review before relying on an approval.
Sources: Va. Code § 13.1-742: corporate dissolution authorization · Va. Code § 13.1-743: corporate articles of dissolution
Review the entity documents, voting rights, dissolution provisions, and any buy-sell agreement. A negotiated buyout, business sale, or agreed wind-down may be possible. If those options fail, judicial dissolution depends on the entity-specific legal standard and the evidence. Disagreement alone does not establish a right to shut down the business or take its assets.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-747: corporate judicial dissolution · Va. Code § 13.1-749.1: purchase election in certain corporate dissolution cases
On a member application, a court may dissolve a Virginia LLC when carrying on the business in conformity with its articles of organization and any operating agreement is not reasonably practicable. The agreement, business purpose, management structure, and actual breakdown matter. The shareholder oppression provisions for corporations are not the same test as the LLC judicial dissolution statute.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
For a corporation that is not a public corporation, specified shareholder grounds include qualifying director deadlock, illegal or oppressive conduct, fraud, certain shareholder voting deadlocks, and misapplied or wasted assets. The statute also provides separate routes in qualifying creditor and other proceedings. Each route has its own conditions; an unhappy owner or unpaid invoice alone does not establish them.
Sources: Va. Code § 13.1-747: corporate judicial dissolution
Yes, a negotiated buyout may preserve the operating business while an owner exits. Review valuation, financing, releases, guarantees, and the governing agreement. In certain Virginia corporate judicial dissolution proceedings, a statutory election to purchase the petitioning shareholder’s shares may also be available, subject to the articles and procedural deadlines. That statute does not automatically create the same right for LLC members.
Sources: Va. Code § 13.1-749.1: purchase election in certain corporate dissolution cases · Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
Debts do not disappear when operations stop or an entity filing is accepted. Identify lenders, suppliers, employees, tax authorities, disputed claims, and contingent obligations. Address payment, settlements, claim procedures, and any appropriate provision for liabilities before owner distributions. Secured claims, priorities, and insolvency can change the analysis.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-745: effect of corporate dissolution · IRS: closing a business, final returns, payroll, and business accounts
No. An entity closing filing does not itself release a separate personal guarantee. Review the signed guarantee, the underlying loan or lease, and any creditor-approved release. A business sale, owner buyout, or agreement between owners also may leave the creditor’s rights against a guarantor intact unless the creditor agrees otherwise.
Virginia provides optional statutory procedures for handling known claims after dissolution. Whether to use them requires a claims review. Both LLC and stock corporation procedures require at least 120 days for written confirmation of a claim, but the rules for unadmitted claims and commencing proceedings differ. Notices must contain the required information, and some contingent or later-maturing liabilities fall outside those procedures. Do not use one generic notice for every entity.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-746: known claims against a dissolved corporation
No. The effect depends on compliance with the applicable statute, the type of claim, and the relevant limitation period. Virginia LLC and corporation public-notice rules differ, including the permitted publication methods. These procedures can establish claim deadlines, but they do not create a universal deadline measured from the day the doors close. Court-approved security may be an option for certain claims.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-746.1: other claims and public notice · Va. Code § 13.1-746.2: court-approved claim security
Yes. Virginia law preserves remedies for certain rights, claims, and liabilities that existed before LLC cancellation or corporate termination. Pending matters, insurance, claim procedures, and record preservation need attention during the wind-down. Whether a particular claim survives, is timely, or can reach an owner depends on its legal basis and the applicable statutory protections.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-755: survival of remedies after corporate termination
Owner distributions come after the required treatment of debts, liabilities, and claims. For a Virginia LLC, winding up includes paying or discharging obligations, or making reasonably adequate provision for them, before distributing the remaining property. Corporate distributions and termination have their own requirements. An apparent cash surplus is not enough if taxes, lawsuits, guarantees, or other obligations remain unresolved.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-745: effect of corporate dissolution · Va. Code § 13.1-750: corporate articles of termination
Not necessarily. The entity type, governing agreement, ownership rights, prior distributions, capital contributions, and creditor claims all matter. Virginia’s LLC statute supplies a distribution order that applies subject to specified governing-document provisions. A 50/50 ownership arrangement does not answer every question about debts, member loans, reimbursements, or particular assets.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
No. A documented loan and an equity contribution can create different rights. Virginia’s LLC distribution statute includes members who are creditors in the creditor category to the extent permitted by law. That does not automatically put an owner loan ahead of a secured lender or another superior claim. Review the records, enforceability, subordination terms, and applicable priorities.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
A company asset needs a lawful sale, assignment, or distribution; it does not automatically become an owner’s personal property. Check title, liens, valuations, contract restrictions, and required approvals. Virginia corporate dissolution itself does not transfer title to corporate property. Real estate, intellectual property, regulated licenses, and customer contracts may require separate transfer documents or consent.
Sources: Va. Code § 13.1-745: effect of corporate dissolution · Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
No. State-law dissolution and a federal bankruptcy proceeding serve different purposes. If the company cannot meet its obligations, review insolvency and creditor options before transferring assets or paying owners. Dissolution alone does not supply a bankruptcy discharge or erase debt, and payments to insiders can raise additional issues.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-745: effect of corporate dissolution
Usually, the lease and any negotiated termination agreement determine the remaining obligations. Closing operations or dissolving the entity does not itself secure a landlord’s release. Review rent, restoration duties, security deposits, assignment provisions, notice requirements, and any personal guarantee. Document a negotiated exit and identify obligations that continue afterward.
Plan for final compensation, payroll tax deposits and returns, wage reporting, benefits, and any applicable notice obligations. The IRS treats employee payments and employment taxes as separate closing tasks. Coordinate counsel, payroll providers, benefit administrators, and the accountant before the last payroll. Unpaid trust fund taxes can create responsibility beyond the entity itself.
Sources: IRS: closing a business, final returns, payroll, and business accounts
The required federal, Virginia, and local filings depend on the entity’s tax classification, business activities, payroll, and assets. An LLC’s legal form does not by itself identify its federal tax return. Final income and employment returns, information reporting, and corporate dissolution reporting may apply. Coordinate with the accountant, and separately notify Virginia Tax when the business or a location closes.
Sources: IRS: closing a business, final returns, payroll, and business accounts · Virginia Tax: closing your business
No. The IRS treats the EIN as a permanent federal taxpayer identification number and provides a separate procedure for closing the business account. State entity filings do not satisfy that process. The IRS requires outstanding returns and tax payments to be addressed before it can close the account. Keep the confirmation and tax records with the company’s closing file.
Sources: IRS: closing a business, final returns, payroll, and business accounts
Inventory them and assign each a separate closing task. Coordinate local licenses, assumed names, permits, tax accounts, other-state registrations, contracts, and insurance. Keep appropriate banking access while collecting receivables and paying remaining obligations. Review coverage and claim-reporting needs before canceling a policy, and retain an address and contact for later correspondence.
Sources: IRS: closing a business, final returns, payroll, and business accounts · Virginia Tax: closing your business
Dissolution under the formation state’s law and withdrawal or cancellation of the Virginia registration are separate matters. A foreign corporation uses Virginia’s withdrawal procedure; a foreign LLC uses cancellation of its certificate of registration. Both require attention to statutory certifications, taxes, and surviving claims. Also review registrations and obligations in every other state where the company operates.
Sources: Va. Code § 13.1-1056: cancellation of a foreign LLC registration · Va. Code § 13.1-767: withdrawal of a foreign corporation
Reinstatement may be available, depending on the entity, the reason for cancellation or termination, elapsed time, and the statutory conditions. For a Virginia LLC, the Code provides a reinstatement procedure with limits and exceptions. Review the SCC status and notices before choosing reinstatement or a final wind-down. Do not assume that automatic cancellation completed the closing work.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival
There is no single reliable timeline. Owner approvals, asset sales, creditor procedures, litigation, lease negotiations, tax preparation, and final filing requirements can each affect completion. SCC processing is only one part of the work. A business with no unresolved obligations presents a different timeline from one with disputed ownership or significant claims.
Sources: Virginia LLC Act, Article 9: dissolution, winding up, claims, cancellation, and survival · Va. Code § 13.1-750: corporate articles of termination
The scope depends on the entity records, number of owners, condition of the books, assets, creditors, contracts, tax coordination, and whether litigation is necessary. A consultation can identify the required legal work and the proposed fee arrangement. Filing fees, accounting work, valuations, and litigation expenses may be separate from legal fees.
Bring the formation documents, operating agreement or bylaws, ownership records, buy-sell agreements, recent financial statements and tax filings, debts and guarantees, leases, contracts, and any court papers. Include the SCC status, proposed closing date, and known response or hearing deadlines. Preserve accounting, tax, employee, and dispute records; retention periods vary by record type and legal obligations.
Sources: IRS: closing a business, final returns, payroll, and business accounts
Understand what the closing requires
Bring the company records, the unfinished obligations, and the reason for closing. We can help identify the legal work and discuss the next steps.
Contacting the firm does not establish representation or extend a filing, response, or hearing deadline.
Sources reviewed October 3, 2026. LLC and stock corporation requirements differ. Formation-state law, tax classification, contracts, and the facts may change the required work.
General information, not legal or tax advice for a particular business. Illustrations and guide results do not establish approval, solvency, or a right to distribute assets. Representation follows a conflicts check and an agreed engagement.
Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.
Copyright © 2026 Shin Law Office, PLC. All rights reserved.
Powered by HILARTECH, LLC
Copyright © 2026 Shin Law Office, PLC. All rights reserved.
Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.
Guides, finders & calculators
Start with a core guide, or choose a sector for more specific tools.
14 tools
Try a broader phrase such as “contract,” “property,” or “family.”
Ask the firm for helpFind a starting point. Then talk through your situation.