Neighbors & contractors
Negligent Neighbors
Trees, roots, runoff, fire, or work next door affecting your home, land, or structures. Assess the source, condition, notice, conduct, and evidence of responsibility.
Read the related answer
Shin Law Office · Northern Virginia
The damage is personal.
The claim needs proof.
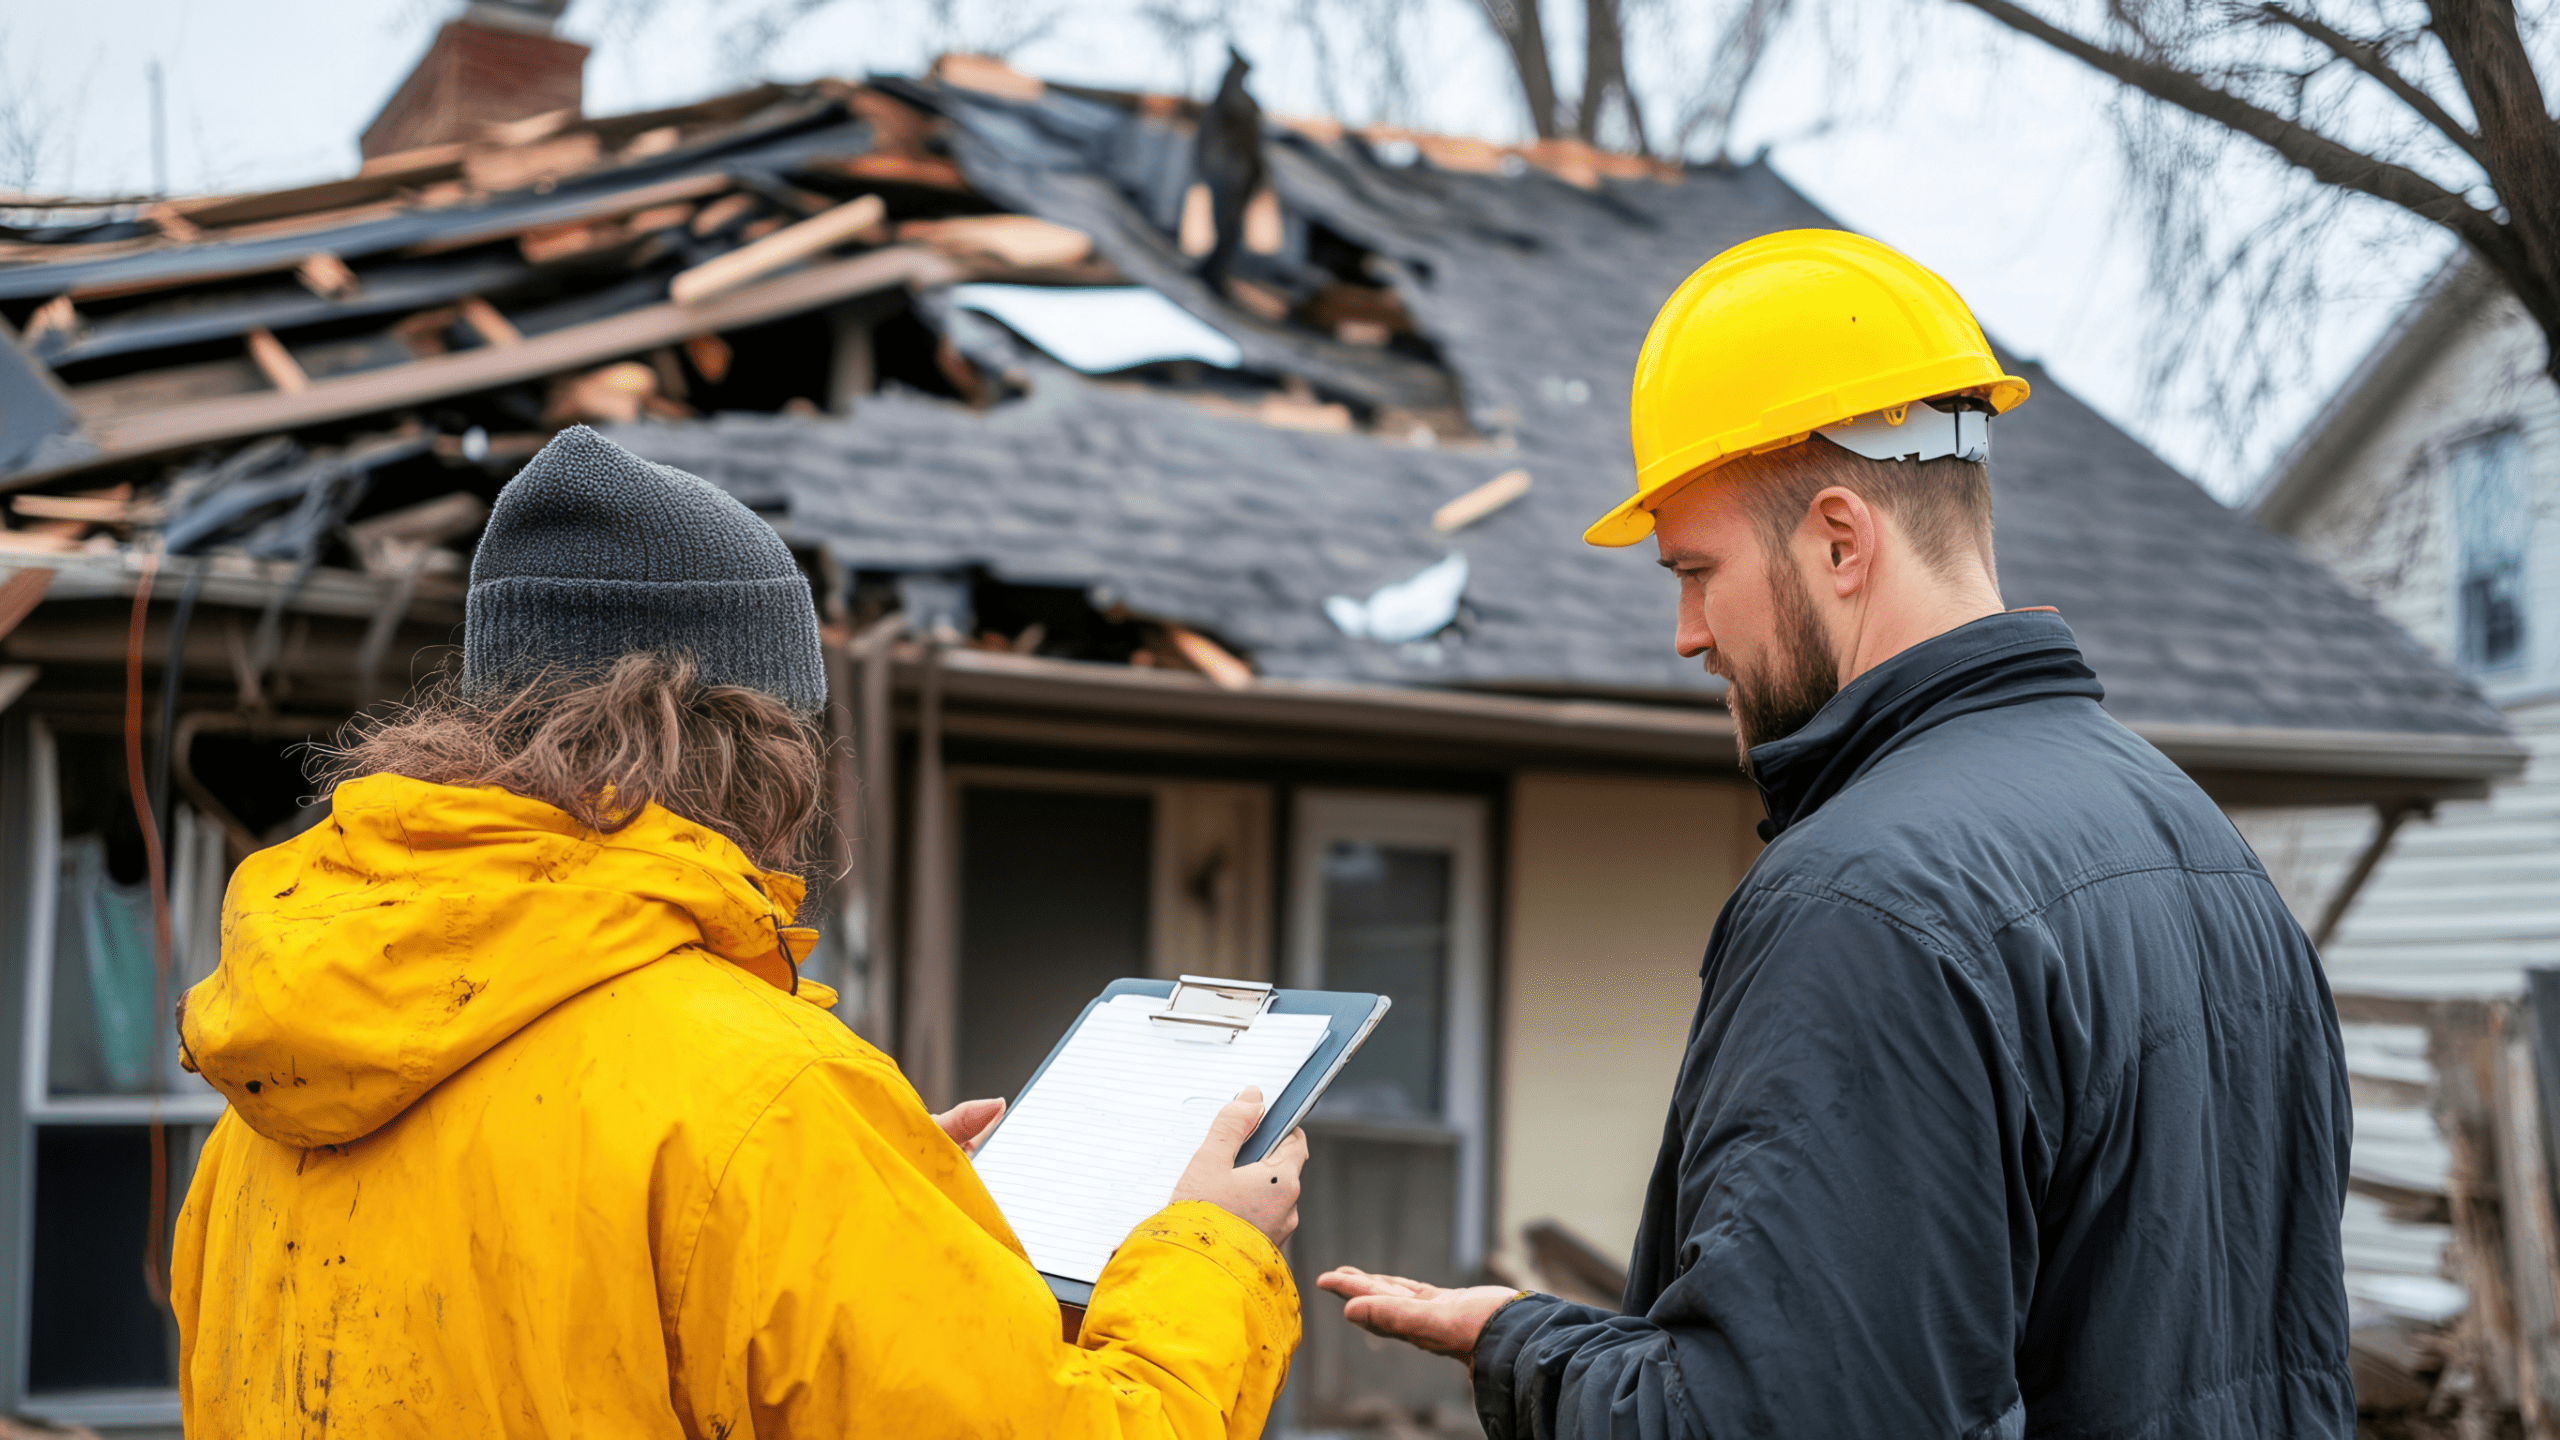
A damaged home, building, or vehicle can interrupt everything around it. We help assess what caused the loss, who may be responsible, what insurance may cover, and the legal steps available to pursue recovery.
Tell us when the damage occurred, what is still happening, and whether repairs, a claim notice, a coverage decision, or a lawsuit needs attention.
Potentially, if the facts support legal responsibility and a provable loss. A claim may involve negligence, trespass, nuisance, a broken contract, or coverage under your own insurance policy. The right route depends on the cause, property, people involved, and governing documents.
Shin Law Office helps Northern Virginia clients connect the physical damage with the evidence, available claims, and appropriate loss measure. We also examine the dates that matter before a general five-year property-injury period is mistaken for the only deadline.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · Abi-Najm v. Concord Condominium, LLC (2010): the source of the legal duty · Virginia Code § 8.01-243(B): limitation for injury to property
Start with what is happening
Choose the closest situation and issue to see relevant records, timing questions, and an explanation.
Step 1 of 2
Select your starting point.
This guide organizes information for a consultation. It does not determine fault, coverage, damages, or your deadline.
Property damage claims we handle
Find help with the source of the loss, the responsible party, the valuation, or an insurance disagreement.
Try “tree roots,” “truck hit my fence,” “city water main,” or “worth less after repair.” Leave out names, claim numbers, and confidential details.
Showing all six topics.
Trees, roots, runoff, fire, or work next door affecting your home, land, or structures. Assess the source, condition, notice, conduct, and evidence of responsibility.
Read the related answerWork that damaged a home, building, or neighboring property. Review the contract, scope, sequence, independent legal duties, and whether a construction time bar applies.
Read the related answerDamage linked to a locality, state agency, authority, or utility. Identify the exact entity, applicable immunity, possible claim, and the correct notice recipient and deadline.
Read the related answerA vehicle or machine that damaged a building, fence, driveway, or land, or a damaged vehicle itself. Review the operator, possible business responsibility, insurance, and loss evidence.
Read the related answerA supported assessment of value lost because of the damage, including any loss remaining after repair where recoverable. The property type, legal measure, and proof control.
Read the related answerYour own insurer’s denial, delay, or disputed valuation. Review the policy, covered cause, exclusions, deductibles, conditions, appraisal provisions, and suit deadline.
Read the related answerChoose “All topics” to broaden the results, or contact the firm about the incident, damage, and documents you have.
Discuss your situationA claim begins with the evidence
A cracked foundation, flooded room, broken fence, or damaged storefront tells you that something went wrong. It may not tell you whether the cause was a recent incident, earlier deterioration, several contributing conditions, or work performed by more than one party.
A useful investigation connects the event to the damage and the duty that may have been violated. It also preserves evidence that could support or challenge the claim, so decisions rest on a complete record.
Sources: Virginia Code § 8.01-379.2:1: preservation and loss of evidence · Virginia Model Jury Instructions: negligence, mitigation, and property damages
What evidence should I gather?| Question | What to review | Why it matters |
|---|---|---|
| Cause of the damage | Scene evidence, inspections, timing, and prior condition. | What caused this loss, and what other explanations need review? |
| Legal responsibility | Duties, conduct, control, contracts, and defenses. | Who may be liable, under which claim, and for which damage? |
| Insurance coverage | The complete policy, endorsements, and claim correspondence. | Is this a covered loss, subject to which conditions and limits? |
| Recoverable amount | Repair scopes, valuations, receipts, and loss-of-use records. | Which measure applies, and which items are supported without overlap? |
A contractor’s estimate, an adjuster’s position, and an incident report can be useful evidence. None automatically resolves every legal or coverage question.
Virginia notice and timing
The general Virginia limitation for injury to property is five years from accrual. The ordinary accrual rule focuses on when injury occurred, not simply when damage was discovered. Other causes of action and exceptions require separate analysis.
Sources: Virginia Code § 8.01-243(B): limitation for injury to property · Virginia Code § 8.01-230: when a claim accrues
For qualifying negligence claims against a county, city, or town, the notice period is generally six months. For a covered Virginia Tort Claims Act claim, notice is generally required within one year. The recipient, content, receipt, exceptions, and separate suit requirements matter.
Sources: Virginia Code § 15.2-209: local-government negligence notice · Virginia Tort Claims Act: liability, notice, and suit requirements
Identify the rule before calculating the date
A policy may impose its own reporting, proof, repair, appraisal, and suit requirements. Construction-related repose can raise a separate time bar. Do not assume a claim number, ongoing repairs, or negotiations preserve every legal deadline.
Sources: Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation · Virginia Code § 8.01-250: construction-related statute of repose
Read about insurance suit timingThe source changes the analysis
The same repair bill may sit behind very different duties, defenses, insurance questions, and procedures.
Tree roots, altered drainage, fire, grading, or excavation can raise distinct issues. Identify the condition, the source, any relevant warnings, and the damage actually caused.
A harmful encroaching root system is different from ordinary leaves or shade. A storm-related fallen tree also calls for its own factual review.
Sources: Fancher v. Fagella (2007): harmful encroaching trees and roots · Virginia Model Jury Instructions: negligence, mitigation, and property damages
Review neighbor claimsExamine the promised work, the property affected, and whether the alleged duty comes from a contract or exists independently under law.
Defective performance does not automatically create a negligence claim. Project dates, insurance terms, and construction-related time bars may be as important as the repair scope.
Sources: Abi-Najm v. Concord Condominium, LLC (2010): the source of the legal duty · Virginia Code § 8.01-250: construction-related statute of repose
Review contractor claimsConfirm the exact legal entity. A city department, state agency, public authority, private utility, and contractor do not share one liability rule.
Notice compliance does not remove immunity. A qualifying public-use taking or damaging claim requires a different analysis from an ordinary negligence claim.
Sources: Virginia Code § 15.2-209: local-government negligence notice · Virginia Tort Claims Act: liability, notice, and suit requirements · Virginia Constitution, Article I, § 11: property taken or damaged for public use
Review public-entity issuesRepair scope, value, and lost use
The cost of restoring property is a starting question. A claim may also require evidence of prior value, salvage, remaining depreciation, or a period of lost use. Which items are recoverable depends on the property and legal theory.
The rules for land and buildings, vehicles and other movable property, and benefits under your own policy may differ. Evaluate restoration and valuation together so a proposed demand neither overlooks a supported loss nor counts the same harm twice.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · 7-Eleven, Inc. v. Department of Environmental Quality (2003): real-property loss measures · Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation
Understand diminished valueProtect the claim while addressing the damage
The practical response should account for safety, inspections, necessary work, and the record a later claim may require.
Document what will change
Photograph conditions when safe, retain relevant materials where practical, and coordinate inspection opportunities. Identify what must be removed, why, and who will document it.
Virginia law can impose evidence-preservation duties when litigation is reasonably foreseeable. A dispute about discarded or altered evidence can complicate the underlying claim.
Sources: Virginia Code § 8.01-379.2:1: preservation and loss of evidence
Limit further damage
Arrange appropriate help for hazards and reasonable measures to prevent additional loss. Keep an itemized record of emergency work, dates, photographs, and expenses.
Preservation and mitigation need to be coordinated. They do not require you to leave dangerous conditions or avoidable ongoing damage unaddressed.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · Virginia SCC: insured homeowners’ guide to disaster losses
Address continuing harm
A repair may be temporary if the underlying problem continues. Assess whether a negotiated correction, access agreement, technical remedy, or court order could address it.
Temporary injunctive relief has distinct legal and evidentiary requirements. The existence of damage alone does not establish entitlement to an injunction.
Sources: Virginia Supreme Court Rule 3:26: temporary injunctive relief
Injunctions & emergency reliefCoverage, claims, and resolution
Your own coverage claim and the claim against a responsible person may proceed under different obligations.
Review the entire policy, endorsements, exclusions, deductibles, and written explanation of the insurer’s decision. Separate a coverage disagreement from a disagreement over scope or amount.
Appraisal may address valuation questions without resolving every coverage issue. Its effect depends on the policy and applicable law.
Sources: Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation
Read about a denied or reduced claimDocument payments, depreciation, deductible amounts, and unresolved items. Review any replacement-cost conditions before assuming all benefits have been exhausted.
Coordinate settlements and releases with any insurer subrogation rights. The wording of a release may reach beyond the specific repair item you intended to settle.
Sources: Virginia Code § 38.2-207: insurer subrogation rights · Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation
Read about insurance paymentsDiscuss claim value, liability proof, technical experts, legal fees, and likely work. A reasoned plan may involve documentation, negotiation, a policy process, or litigation.
Attorney fees are not automatically shifted to the other side. Insurer bad-faith fee recovery requires the statutory conditions and an appropriate court finding.
Sources: Virginia Code § 38.2-209: attorney fees for certain insurer bad-faith findings
Read about insurer bad faithBefore the consultation
Keep originals and complete correspondence in your lawful possession. Include facts that may support or challenge the claim.
What working with us looks like
Review the property, what happened, ongoing conditions, planned repairs, and documents that may trigger a deadline.
Examine the factual record, governing duties, potential defendants, defenses, insurance, and any need for technical experts.
Compare repair scope, valuation, temporary losses, legal measures, policy obligations, and available dispute procedures.
If engaged, carry out the defined scope, which may include evidence work, notices, negotiation, a policy process, or litigation.
Shin Law Office
Founder
A damaged home or business can leave you managing contractors, insurers, expenses, and uncertainty at the same time. A focused legal review connects those immediate problems with the evidence and decisions that affect the claim.
Shin Law Office assists with property-damage disputes and related civil litigation in Northern Virginia. The initial review addresses the legal issues, available records, timing, and the scope and fees of any agreed representation.
Meet Anthony I. ShinNorthern Virginia
Shin Law Office helps Northern Virginia clients assess property damage involving neighbors, contractors, vehicles, utilities, public entities, and insurance disputes.
Tell us what was damaged, when it happened, and what the other party or insurer has said. Identify any continuing harm, upcoming repair work, claim notice, demand, or lawsuit.
Schedule a ConsultationOffice: 571-445-6565
Cell: 571-215-8823
Fax: 703-442-8938
118 Edwards Ferry Road, N.E.
Unit 110
Leesburg, VA 20176
8300 Arlington Boulevard
#B2
Fairfax, VA 22031
Property damage FAQs
These answers focus on Virginia. The property, cause, legal entity, claim, policy, evidence, and procedural stage can change the analysis.
Discuss your questionA property damage claim seeks relief for harm to land, a building, a vehicle, equipment, or other property. The legal basis may involve negligence, trespass, nuisance, breach of contract, or rights under an insurance policy. You must connect the responsible party or coverage obligation with the damage and a supported measure of loss. Damage alone does not prove that someone else is legally liable.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · Abi-Najm v. Concord Condominium, LLC (2010): the source of the legal duty
Protect people and address immediate hazards. When safe, photograph the scene, record the date and circumstances, identify witnesses, and preserve relevant materials and communications. Notify applicable insurers promptly. Arrange reasonable protective work to prevent additional damage while documenting what changes. An urgent repair should not be delayed simply to leave the scene untouched.
Sources: Virginia SCC: insured homeowners’ guide to disaster losses · Virginia Model Jury Instructions: negligence, mitigation, and property damages · Virginia Code § 8.01-379.2:1: preservation and loss of evidence
Necessary emergency protection and final restoration are different decisions. Document conditions before work when safely possible, keep receipts, and arrange reasonable inspection and evidence-preservation opportunities before materials are discarded or altered. Follow applicable policy requirements and discuss disputed or destructive work promptly. Evidence preservation does not mean allowing avoidable damage to continue or leaving an unsafe condition in place.
Sources: Virginia SCC: insured homeowners’ guide to disaster losses · Virginia Code § 8.01-379.2:1: preservation and loss of evidence · Virginia Model Jury Instructions: negligence, mitigation, and property damages
Useful evidence may include dated photographs, video, incident and inspection reports, prior-condition records, contracts, permits, maintenance history, notices, weather information, and witness accounts. An engineer, arborist, contractor, appraiser, or other qualified expert may be needed to address cause, repair scope, or value. A repair estimate can show proposed cost without establishing who caused the problem.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · Virginia Code § 8.01-379.2:1: preservation and loss of evidence
Virginia Code § 8.01-243(B) generally provides five years from accrual for an action for injury to property. That is not a universal deadline for every property-related dispute. Government notice, insurance-policy suits, contract claims, construction statutes of repose, and other rules may operate differently or require earlier action. Have the claim type, relevant dates, and potential defendants reviewed promptly.
Sources: Virginia Code § 8.01-243(B): limitation for injury to property · Virginia Code § 8.01-230: when a claim accrues · Virginia Code § 15.2-209: local-government negligence notice · Virginia Tort Claims Act: liability, notice, and suit requirements · Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation · Virginia Code § 8.01-250: construction-related statute of repose
Not necessarily. Virginia’s general accrual rule for property injury ordinarily looks to when the injury was sustained, rather than when the resulting damage was discovered, subject to applicable exceptions. Hidden damage, repeated events, continuing conditions, and different causes of action require careful analysis. Do not assume a new inspection report or later repair estimate starts a fresh limitation period.
For a cognizable negligence claim against a county, city, or town, § 15.2-209 generally requires a written statement describing the claim and the time and place of injury within six months after accrual. The statute identifies the proper recipients and treats notice as filed when received. It also contains actual-knowledge and disability provisions. Notice compliance does not waive sovereign immunity or itself establish liability.
Sources: Virginia Code § 15.2-209: local-government negligence notice
For a claim covered by the Virginia Tort Claims Act, the notice period is generally one year after accrual. The required content, recipient, and proof of receipt matter; the statute provides special direction for a claim alleging VDOT liability. Actual-knowledge and disability provisions may apply. Separate rules govern when a lawsuit may begin and its filing deadline, so a timely notice is not the last procedural step.
Sources: Virginia Tort Claims Act: liability, notice, and suit requirements
No. A private utility, a municipal department, a public authority, a state agency, and a contractor can have different legal status and rules. Identify the exact legal entity, service or project, alleged conduct, and any easement or contract. Do not assume that a utility is the Commonwealth, that every public entity falls under the Virginia Tort Claims Act, or that giving notice proves a valid claim.
Sources: Virginia Code § 15.2-209: local-government negligence notice · Virginia Tort Claims Act: liability, notice, and suit requirements · Virginia Constitution, Article I, § 11: property taken or damaged for public use
Possibly, but the legal route matters. A negligence claim may face immunity, statutory limits, and notice requirements. A qualifying claim for property taken or damaged for public use under the Virginia Constitution involves a different legal framework. Not every government-related loss is an inverse-condemnation claim. Review the project, public use, causation, property rights, and exact entity before choosing a theory.
Sources: Virginia Tort Claims Act: liability, notice, and suit requirements · Virginia Code § 15.2-209: local-government negligence notice · Virginia Constitution, Article I, § 11: property taken or damaged for public use
No. The type of tree problem and the facts matter. Fancher v. Fagella addresses encroaching branches or roots that cause actual harm or an imminent danger of actual harm to adjoining property; ordinary shade, leaves, or mere encroachment is not enough by itself. A fallen-tree or storm-loss case may require a different negligence analysis. Preserve condition evidence, prior warnings, inspection findings, and the circumstances of the damage.
Sources: Fancher v. Fagella (2007): harmful encroaching trees and roots · Virginia Model Jury Instructions: negligence, mitigation, and property damages
Potentially. Identify where the water came from, whether grading, drainage, construction, maintenance, or another condition changed its flow, and what damage followed. Surveys, photographs taken during an event, engineering findings, prior complaints, and repair records may be important. The fact that water arrived from another property does not by itself resolve negligence, nuisance, property rights, or insurance coverage.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · Abi-Najm v. Concord Condominium, LLC (2010): the source of the legal duty
Potentially, but identify the duty and the loss first. A contract may govern deficient work or an unmet project promise, while an independent legal duty may support a tort claim in appropriate circumstances. Virginia’s economic-loss principles can limit attempts to turn a contractual failure into negligence. Review the contract, work performed, affected property, cause of damage, and responsible parties together.
Sources: Abi-Najm v. Concord Condominium, LLC (2010): the source of the legal duty · Virginia Code § 8.01-246: contract limitation periods
Yes, potentially. Virginia Code § 8.01-250 generally bars specified actions arising from defective and unsafe improvements to real property more than five years after the relevant design, planning, surveying, supervision, or construction services were performed or furnished. It has exceptions and does not cover every defendant or every claim. This statute of repose differs from a limitation period measured from injury or breach.
Sources: Virginia Code § 8.01-250: construction-related statute of repose · Virginia Code § 8.01-243(B): limitation for injury to property · Virginia Code § 8.01-246: contract limitation periods
Start with the operator’s conduct, ownership and control, and any relevant employer or contractor relationship. Responsibility may extend beyond the driver only when the facts and law support it. Preserve footage, incident reports, vehicle information, work assignments, witness accounts, and the damage record. Insurance availability is a separate question from liability, and an accident report alone does not decide the civil claim.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages
Negligence generally concerns a failure to meet a legal duty of care that causes damage. Trespass concerns an unauthorized invasion of protected property rights. A contract claim concerns obligations the parties agreed to perform. The same event may raise more than one issue, but each claim has its own elements, defenses, and potential remedies. The source of the duty helps determine which theory fits.
Sources: Abi-Najm v. Concord Condominium, LLC (2010): the source of the legal duty · Virginia Model Jury Instructions: negligence, mitigation, and property damages
Yes. In an ordinary Virginia negligence case, contributory negligence that proximately contributes to the injury can bar recovery, subject to applicable exceptions. Separately, a failure to take reasonable steps to limit additional damage may reduce recoverable loss. These are distinct questions. Share prior conditions, maintenance records, warnings, and your response to the incident so the evidence can be assessed fairly.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages
The measure depends on the property, claim, and evidence. Review reasonable restoration costs, applicable before-and-after value measures, any recoverable loss remaining after repair, and supported incidental or loss-of-use items. Real property and movable personal property do not always use the same analysis. These categories are not an automatic stack of payments, and the same injury cannot be counted twice.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · 7-Eleven, Inc. v. Department of Environmental Quality (2003): real-property loss measures
Sometimes. A property item may retain a provable loss in value even after adequate repairs, but entitlement and measurement depend on the type of property and the governing claim or policy. Evidence may include appraisals, comparable sales, prior condition, repair quality, and remaining defects. Do not assume a fixed percentage applies or that a personal-property rule automatically governs a home or land.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · 7-Eleven, Inc. v. Department of Environmental Quality (2003): real-property loss measures
For totally damaged personal property, Virginia’s model instructions use the difference between value immediately before and after the event, plus proven necessary and reasonable expenses. A repairable loss may call for a repair-cost measure with an appropriate allowance for depreciation. Salvage, prior condition, repairability, and the evidence affect the analysis. A policy may define actual cash value and replacement-cost benefits separately.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation
Possibly, depending on the claim or policy, causation, reasonableness, proof, and applicable limits. Keep dates of lost use, receipts, leases, rental records, business records, and evidence explaining why the expense or interruption resulted from the damage. Lost revenue is not automatically lost profit. Avoid assuming that every inconvenience or consequential loss is recoverable in every property case.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · 7-Eleven, Inc. v. Department of Environmental Quality (2003): real-property loss measures · Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation
Both may need review. A first-party insurance claim depends on your policy, covered causes, exclusions, limits, deductibles, and conditions. A claim against another person depends on legal responsibility and provable damages. Reporting a loss or negotiating with an adjuster does not automatically preserve a lawsuit deadline. Coordinate payments, releases, and any insurer subrogation rights.
Sources: Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation · Virginia Code § 38.2-207: insurer subrogation rights
Get the reason in writing and compare it with the complete policy and the evidence. Determine whether the dispute concerns coverage, the cause of loss, repair scope, depreciation, replacement cost, or valuation. A focused response may require additional records, expert analysis, appraisal where appropriate, negotiation, or litigation. A low offer or denial alone does not establish insurer bad faith.
Sources: Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation · Virginia Code § 38.2-209: attorney fees for certain insurer bad-faith findings
Not necessarily. An appraisal provision commonly addresses a disagreement about the amount of loss, while coverage and legal interpretation may remain separate. The policy wording, disputed questions, and applicable law determine the process and effect. Before demanding or participating in appraisal, review costs, selection procedures, scope, and whether any notice or suit deadline still needs independent protection.
Sources: Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation
Do not assume so. A suit under your policy may have a contractual or statutory suit limitation that differs from a claim against the person who caused the damage. Virginia’s standard fire-policy provisions include a two-year period measured from inception of the loss, and other policy conditions also matter. Review the actual policy and applicable law promptly; negotiations or a complaint should not be assumed to extend the period.
Sources: Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation · Virginia Code § 8.01-243(B): limitation for injury to property
Virginia Code § 38.2-209 permits costs and reasonable attorney fees in qualifying insured-versus-insurer litigation when the court makes the required finding that the insurer acted without good faith in denying coverage or failing or refusing payment. The statute does not make every denial bad faith or create standing where it otherwise does not exist. Fee recovery requires an applicable legal basis and is not assured.
Sources: Virginia Code § 38.2-209: attorney fees for certain insurer bad-faith findings
Review the payment, policy, deductible, unresolved items, and any subrogation rights. An insurer that pays may acquire rights to pursue a responsible party. Coordinate the handling of the remaining claim and any settlement release so you do not impair rights held by the insurer or dispose of unresolved claims unintentionally. Insurance payments and the legal damages analysis should be reviewed together.
Sources: Virginia Code § 38.2-207: insurer subrogation rights · Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation
Potentially. A preliminary injunction ordinarily requires a showing that irreparable harm is more likely than not without relief, a supported claim more likely than not to succeed, a favorable balance of hardships, and no conflict with the public interest. Rule 3:26 includes a rare exception to the usual merits requirement and separate temporary-restraining-order provisions; a statute may supply different criteria. A repair bill alone does not establish entitlement. Continuing harmful tree encroachment is one fact-specific example in Virginia case law.
Sources: Virginia Supreme Court Rule 3:26: temporary injunctive relief · Fancher v. Fagella (2007): harmful encroaching trees and roots
Preserve the complete demand or lawsuit, record when and how it was received, and notify potentially applicable liability insurers promptly. Keep relevant photos, footage, contracts, maintenance records, work files, and communications. Review causation, defenses, insurance, and any response deadline before making substantive admissions or agreeing to repairs or payment. A request for consultation does not substitute for a required court response.
Sources: Virginia Model Jury Instructions: negligence, mitigation, and property damages · Virginia Code § 8.01-379.2:1: preservation and loss of evidence · Virginia Code § 38.2-2105: fire-policy conditions, appraisal, and suit limitation
Bring a short timeline, photographs, the property’s prior-condition records, inspection findings, itemized estimates, contracts, complete insurance policies, coverage letters, payments, notices, and any court papers. Identify ongoing hazards, upcoming repairs, and the result you want. The initial review should address the legal route, proof, timing, likely work, and fee arrangement. Settlement, litigation, and the scope of representation depend on the facts and an agreed engagement.
Understand the damage. Preserve your options.
Bring the photographs, estimates, policies, and correspondence. We can help assess responsibility, coverage, proof, and the legal steps that may support recovery.
Contacting the firm does not establish representation or extend a notice, policy, statutory, response, or court deadline.
Virginia statutes, court decisions, court guidance, and insurance guidance reviewed October 3, 2026. The claim type, property, entity, applicable law, and policy require individual review.
General information, not legal advice for a particular claim. Illustrations and guide results do not establish liability, coverage, value, available relief, or deadlines. Representation follows a conflicts check and an agreed engagement.
Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.
Copyright © 2026 Shin Law Office, PLC. All rights reserved.
Powered by HILARTECH, LLC
Copyright © 2026 Shin Law Office, PLC. All rights reserved.
Reproduction of any content on this site is prohibited except for individual, non-commercial, informational use. This limited permission does not allow modification, distribution, or incorporation of any content into other works or publications in any medium. You may not reproduce or distribute content from this site to any third party.
Guides, finders & calculators
Start with a core guide, or choose a sector for more specific tools.
14 tools
Try a broader phrase such as “contract,” “property,” or “family.”
Ask the firm for helpFind a starting point. Then talk through your situation.